Investing to profit from the AI build-out can be difficult. There are so many options, ranging from computing companies to application plays to energy companies. All of these are bound to benefit in one way, but choosing the best isn’t easy. However, I think there’s one company that may cut through all of that noise and provide a top investment opportunity: Taiwan Semiconductor (NYSE: TSM).
It looks like a practically guaranteed winner in the AI build-out, and it’s easy to see why.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a “Double Down” signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same “Total Conviction” signal is flashing for a company 1/100th the size of Nvidia. Continue »
Taiwan Semiconductor has a grip on the chip industry
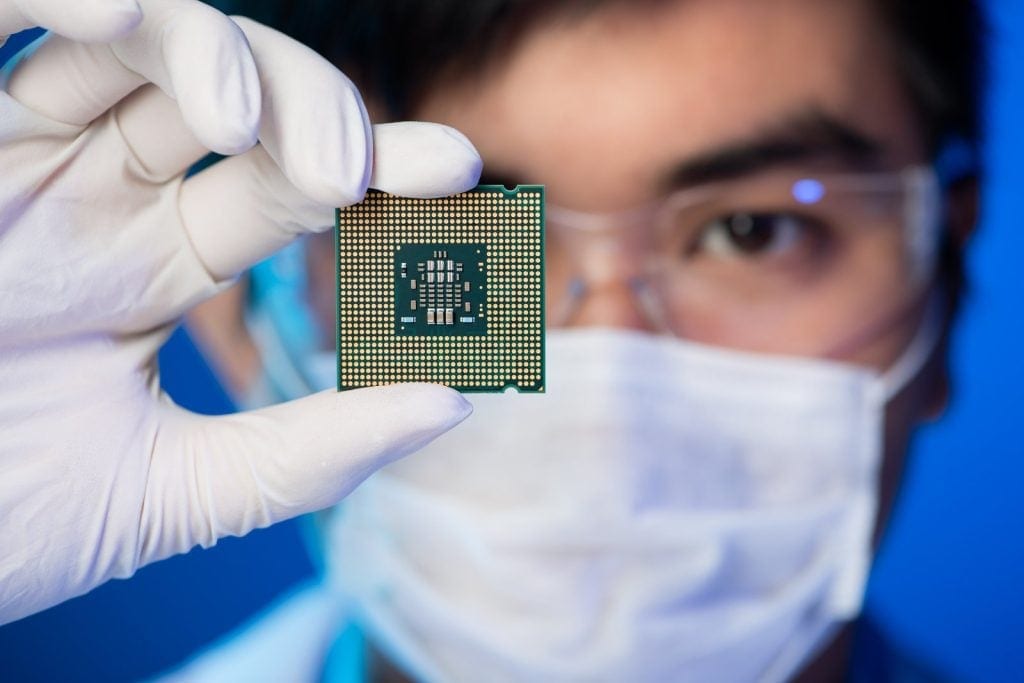
Taiwan Semiconductor is a logic chip fabrication company: Simply put, it manufactures the chips designed by its clients, most of which lack any foundries of their own. All of the major AI computing unit manufacturers — Nvidia (NASDAQ: NVDA), AMD (NASDAQ: AMD), and Broadcom (NASDAQ: AVGO), and others — utilize TSMC’s services.
They have to, as no other chip foundry has the capacity to serve as a viable alternative. During Q2, TSMC’s massive manufacturing infrastructure allowed it to take in 72.5% of chip foundry revenue in the world. That capacity dominance makes it difficult for any other company to rise and steal its leading clients away.
However, even if it were more of an option, TSMC’s clients don’t have many reasons to want to switch foundry partners, either. TSMC has best-in-class technology and a reputation for fantastic production yields. That makes it a great company to partner with. There’s a reason why TSMC has grown to become the giant that it is.
As for the AI build-out, as long as companies continue to need more and more computing capacity, TSMC will see large orders for chips. It has projected that from 2024 to 2029, revenues from its AI chip business will grow at a compound annual rate in the mid-to-high 50% range, and during the company’s Q3 conference call, CEO C.C. Wei said that its growth rate “probably will be higher.”
That will benefit shareholders immensely.
Lastly, the stock isn’t priced outrageously.
TSM PE Ratio (Forward) data by YCharts.
At 23 times forward expected earnings, Taiwan Semiconductor is trading at a discount relative to its typical level at this time of year. So, not only is it a great long-term investment in the AI build-out, but it’s also a timely buy. Opportunities like this don’t often appear, and investors should take advantage of the stock while it’s a bit cheaper than historical levels. While TSMC may not provide the best long-term AI returns, I am confident that it is practically guaranteed to do well.
Should you buy stock in Taiwan Semiconductor Manufacturing right now?
Before you buy stock in Taiwan Semiconductor Manufacturing, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Taiwan Semiconductor Manufacturing wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004… if you invested $1,000 at the time of our recommendation, you’d have $341,966!* Or when Nvidia made this list on April 15, 2005… if you invested $1,000 at the time of our recommendation, you’d have $1,146,819!*
Now, it’s worth noting Stock Advisor’s total average return is 852% — a market-crushing outperformance compared to 203% for the S&P 500. Don’t miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of November 8, 2026.
Keithen Drury has positions in Broadcom, Nvidia, and Taiwan Semiconductor Manufacturing. The Motley Fool has positions in and recommends Advanced Micro Devices, Broadcom, Nvidia, and Taiwan Semiconductor Manufacturing. The Motley Fool has a disclosure policy.