Key Points
-
Social Security’s cost-of-living adjustment (COLA) will be announced for the program’s more than 71 million traditional beneficiaries on Oct. 14.
-
Two of President Donald Trump’s policies should lead to a well-above-average Social Security raise next year, and a pleasant surprise for tens of millions of retirees.
-
Unfortunately, Social Security’s Trump bump can worsen the program’s already precarious financial outlook.
-
One of the most anticipated days of the year for Social Security’s more than 71 million traditional beneficiaries (retired workers, workers with disabilities, and survivors of deceased workers) is less than four weeks away.
On Oct. 14, the U.S. Bureau of Labor Statistics will publish the September inflation report, providing the final puzzle piece needed to calculate and announce Social Security’s 2027 cost-of-living adjustment (COLA). Social Security’s COLA is the near-annual “raise” passed on to Social Security recipients that accounts for inflation (i.e., rising prices).
Missed AI’s “Act 1”? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn’t buy Nvidia in 2005. But according to our analysts, we’re only at the end of “Act 1″—the R&D phase. “Act 2” is the global rollout. Continue »
Since the Consumer Price Index for Urban Wage Earners and Clerical Workers became Social Security’s inflation-measuring yardstick in 1975, beneficiaries have received a raise in all but three years (2010, 2011, and 2016). However, next year’s payout hike will feature something relatively unique: a “Trump bump.”

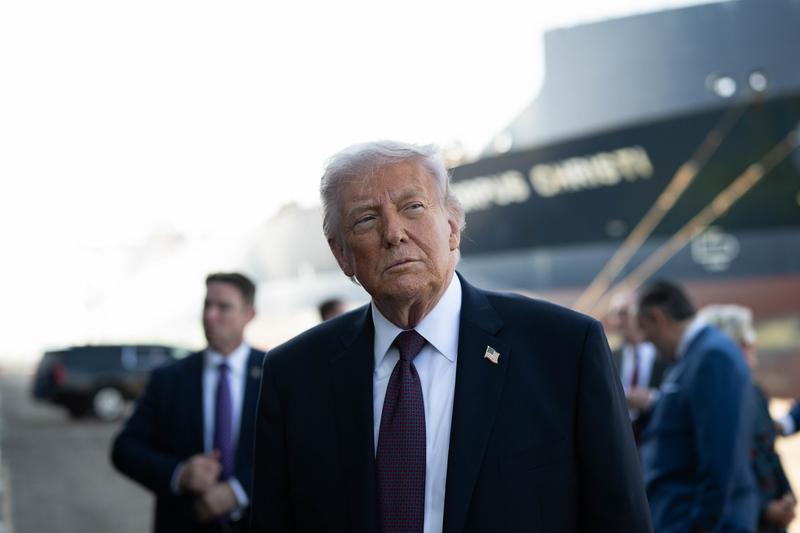
President Trump’s impact on Social Security comes with advantages and drawbacks. Image source: Official White House Photo by Molly Riley.
President Donald Trump’s policies are directly influencing how much Social Security beneficiaries will receive each month, and have set next year up as a good-news/bad-news scenario.
The good: A first-in-four-year silver lining awaits tens of millions of retirees
When the U.S. economy is expanding, it’s normal for businesses to possess a modest degree of pricing power over their goods and services, leading to a moderate level of inflation. However, two of President Trump’s policies, tariffs and the Iran war, are boosting the prevailing inflation rate beyond modest levels.
In April 2025, Trump unveiled his long-touted tariff and trade policy, featuring sweeping global tariffs and higher reciprocal tariffs on dozens of countries. Despite the U.S. Supreme Court invalidating these tariffs in February 2026, they provided a lift to consumer prices last year, thereby modestly boosting Social Security’s COLA in 2026.
The same effect is expected in 2027. In July, the Trump administration announced new global tariffs (using a different justification) on more than 80 countries, ranging from 10% to 12.5%. Assigning duties to imported goods can increase domestic production costs and raise consumer prices.
However, the Iran war is having a considerably larger impact on inflation. The closure of the Strait of Hormuz sent fuel prices soaring. Additionally, the effects of Iran-war-driven inflation are beginning to show up in the broader economy.
The result of Trumpflation (inflation that’s specifically driven by President Trump’s policies) is above-average inflation and, therefore, a beefier 2027 COLA.
Both The Senior Citizens League, a nonpartisan senior advocacy group, and Mary Johnson, an independent Social Security and Medicare policy analyst, are forecasting a 3.5% increase in Social Security payouts next year. This outsize COLA should provide a silver lining for tens of millions of retirees for the first time since 2023.
Close to half of Social Security’s age 65-and-up crowd is enrolled in traditional Medicare, which consists of Parts A (in-hospital stays), B (outpatient services), and D (prescription drugs). While Part A costs nothing for approximately 99% of retirees, Part B has a standard monthly premium of $202.90 in 2026.
Throughout the 21st century, the standard monthly Part B premium has pretty consistently risen at a faster pace than Social Security’s COLA. For instance, while beneficiaries received respective raises of 3.2% (2024), 2.5% (2025), and 2.8% (2026), Medicare’s Part B premium climbed by 5.9% (2024), 5.9%, and 9.7% (2026). Rapidly rising Part B premiums can partially or fully offset the impact of Social Security’s annual COLA.
According to the 2026 Medicare Trustees Report, the standard Part B premium is forecast to rise by 3.25% next year. Based on projections, Social Security’s raise (3.5%) will be higher, on a percentage basis, than Medicare’s Part B premium for the first time since 2023. That’s a silver lining worth looking forward to for tens of millions of retirees.

Image source: Getty Images.
The bad: Outsize Trump bumps can accelerate the timeline to sweeping Social Security benefit cuts
Unfortunately, larger monthly payouts, courtesy of the aforementioned Trump bump, come with potentially dire consequences for Social Security’s current and future beneficiaries.
Long before President Trump took office for either of his non-consecutive terms, the annual Social Security Board of Trustees Report had been cautioning of a long-term (75-year) unfunded obligation. Since 1985, the Trustees have forecast that income collected in the 75 years following the release of a report would be insufficient to cover outlays (primarily benefits, but also the administrative expenses to oversee Social Security). Through the year 2100, this funding shortfall has reached an estimated $29.3 trillion.
But the far greater concern for Social Security is the forthcoming depletion of the Old-Age and Survivors Insurance trust fund’s (OASI) asset reserves, estimated to occur by the fourth quarter of 2032. Even though the OASI doesn’t need a cent in its asset reserves to continue making payments (i.e., it won’t go bankrupt), sweeping benefit cuts, estimated at 22%, may be necessary in six years if these reserves are exhausted.
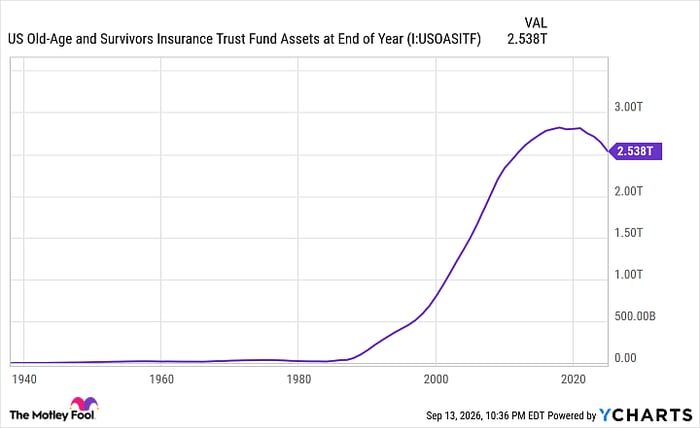
US Old-Age and Survivors Insurance Trust Fund Assets at End of Year data by YCharts
The issue is that this projected timeline to OASI asset reserve depletion could be shifted forward by Social Security’s Trump bump-driven 2027 COLA.
When the Social Security Board of Trustees comes up with its long-term forecasts, one of the variables it considers is the program’s annual cost-of-living adjustment. While modest yearly COLAs are used in the Trustees’ modeling, an estimated 3.5% raise next year would be well above average. In other words, it could drain the OASI’s asset reserves even faster than currently forecast.
While larger nominal monthly checks often lead to big smiles for Social Security’s recipients, there’s a potentially steep price to pay for next year’s Trump bump.
The $23,760 Social Security bonus most retirees completely overlook
If you’re like most Americans, you’re a few years (or more) behind on your retirement savings. But a handful of little-known “Social Security secrets” could help ensure a boost in your retirement income.
One easy trick could pay you as much as $23,760 more… each year! Once you learn how to maximize your Social Security benefits, we think you could retire confidently with the peace of mind we’re all after. Join Stock Advisor to learn more about these strategies.
View the “Social Security secrets” »
The Motley Fool has a disclosure policy.