Key Points
-
TSMC’s October sales surged nicely, and its growth rate has improved in recent months.
-
TSMC can sustain its solid growth amid healthy investments in AI data centers, which explains why the company is increasing capex to boost manufacturing capacity.
-
TSMC’s higher capex bodes well for ASML, which is another key player in the AI ecosystem.
-
The semiconductor sector has been under immense pressure lately, as evidenced by the 17% decline in the PHLX Semiconductor Sector index since the beginning of October. However, results from leading semiconductor companies clearly indicate that the sell-off is overdone.
Taiwan Semiconductor Manufacturing (NYSE:TSM), one of the world’s most important semiconductor companies, just released its October sales figures, providing further evidence that the artificial intelligence (AI) build-out isn’t slowing down. Let’s see how TSMC fared in October before taking a look at some top semiconductor stocks that are worth buying following the recent sell-off.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a “Double Down” signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same “Total Conviction” signal is flashing for a company 1/100th the size of Nvidia. Continue »
Image source: Getty Images.
The AI chip boom will help TSMC sustain its incredible growth
TSMC’s October revenue increased nearly 60% from the year-ago period. What’s worth noting is that its growth has gained solid momentum lately. TSMC’s revenue in July, August, and September increased by 45%, 53%, and 55%, respectively, compared to the respective year-ago periods.
It isn’t surprising to see this acceleration in TSMC’s growth. The company noted on its October earnings call that it is seeing “continued robust multi-year demand from our customers,” driven by the growing adoption of agentic AI and open-source AI models. TSMC management further pointed out that the “value of semiconductors in the global supply chain is set to continue to increase,” as chips will play an essential role in the AI build-out.
TSMC’s revenue has increased by 43.3% in the first 10 months of 2026. The recent acceleration in growth suggests it could exceed its 2026 revenue growth target of 44%. Also, TSMC’s long-term earnings per share (EPS) growth estimates have taken off this year.
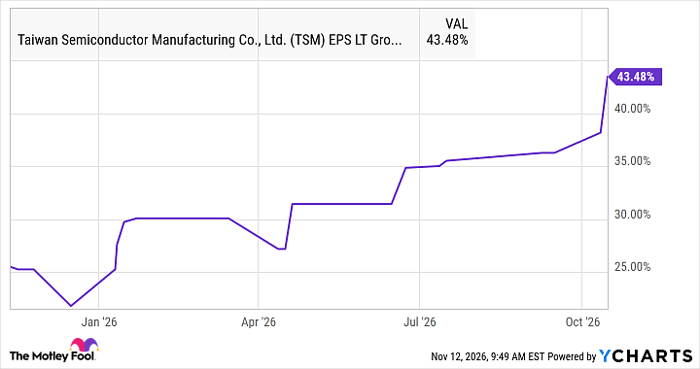
TSM EPS LT Growth Estimates data by YCharts
That’s why buying TSMC stock following its double-digit slide since October’s beginning is a smart move, especially considering that it trades at an attractive 18 times forward earnings. However, this isn’t the only chip stock that’s benefiting from the AI boom. Let’s take a closer look at another name worth buying right now.
This semiconductor company is essential to the AI build-out
TSMC management pointed out last month that it is on track to spend $60-$64 billion on capital expenditure this year. That will be a significant bump over its 2025 capital expenditure of $40.9 billion. The company sees its capital expenditure between 2026 and 2028 to be “significantly higher than the past three years.”
This is great news for ASML Holding (NASDAQ:ASML), which manufactures the extreme ultraviolet (EUV) lithography machines that help TSMC build its advanced AI chips. ASML stock has dropped by more than 15% since the beginning of October. It now trades at 23 times forward earnings, lower than its five-year average forward price-to-earnings (P/E) ratio of 32.5.
That’s quite attractive for a company that reported a 136% year-over-year increase in EPS in Q3 2026. Even better, ASML sees persistently strong demand for its chipmaking equipment over the coming years, outpacing its production capacity.
As a result, the company aims to increase the output of its EUV lithography systems by 30% in 2027. Management is exploring the possibility of increasing output by more than 30% in 2028. Given that ASML has a monopoly in EUV lithography, it can charge customers like TSMC a premium. So, it’s not surprising that its long-term growth estimates have jumped significantly.
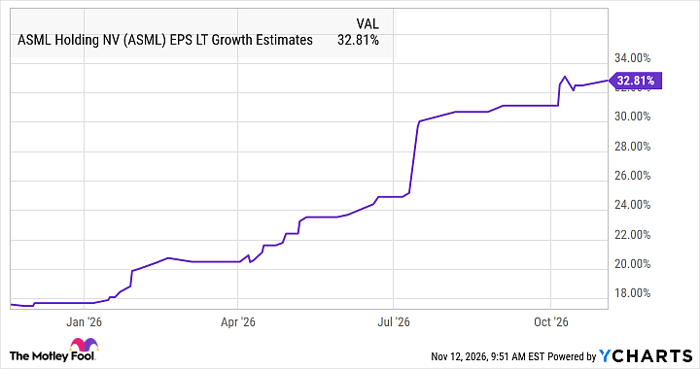
ASML EPS LT Growth Estimates data by YCharts
However, ASML could easily outpace those expectations. Its EPS jumped significantly in Q3, and it can sustain robust long-term growth due to its monopoly, higher capital spending by customers like TSMC, and continued investments in AI infrastructure.
Investors, therefore, can consider adding both ASML and TSMC to their portfolios, as they are well-positioned to capitalize on the AI-fueled chip boom over the long run and are trading at attractive levels.
Should you buy stock in Taiwan Semiconductor Manufacturing right now?
Before you buy stock in Taiwan Semiconductor Manufacturing, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Taiwan Semiconductor Manufacturing wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004… if you invested $1,000 at the time of our recommendation, you’d have $338,083!* Or when Nvidia made this list on April 15, 2005… if you invested $1,000 at the time of our recommendation, you’d have $1,021,163!*
Now, it’s worth noting Stock Advisor’s total average return is 830% — a market-crushing outperformance compared to 209% for the S&P 500. Don’t miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of November 13, 2026.
Harsh Chauhan has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends ASML and Taiwan Semiconductor Manufacturing. The Motley Fool has a disclosure policy.