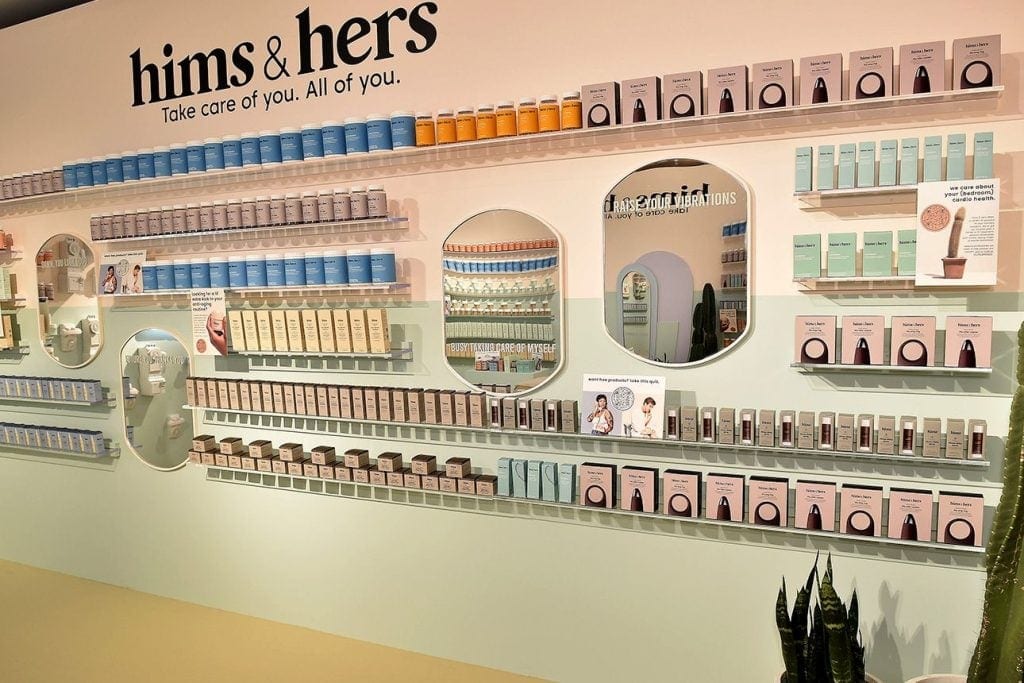
A difficult year for Hims & Hers Health (NYSE:HIMS)got worse after the stock price plummeted 17% following its Q3 earnings report. While the company’s quarterly results were essentially in line with expectations, its Q4 guidance fell short. The stock is now down more than 40% on the year.
However, with a setup for a potential peptide push, now could be the time to buy this growth stock. Let’s take a closer look at the telehealth stock’s most recent results and prospects.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a “Double Down” signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same “Total Conviction” signal is flashing for a company 1/100th the size of Nvidia. Continue »
Image source: Getty Images.
The peptide offering
With the U.S. government allowing compounding pharmacies to begin selling peptide compounds, Hims & Hers will launch its new Peptides+ category at the end of the month. The company has been preparing for this by investing in its supply chain and manufacturing facilities and plans to start by offering sermorelin, glutathione, and NAD+ at launch. BPC-157 and TB-500, which have shown strong promise in healing soft-tissue injuries, will be added later “when the regulatory environment permits.”
However, the company said its peptide launch won’t materially impact its Q4 results, and its quarterly forecast fell short of analyst expectations. The company projected Q4 revenue to rise between 42% and 45% to a range of $875 million and $895 million, while adjusted earnings before interest, taxes, depreciation, and amortization (EBITDA) are forecast to be between $70 million and $90 million. Analysts were looking for revenue of $955.1 million.
For Q3, Hims & Hers reported sales that climbed 49% year over year to $890.4 million. That was around the midpoint of its $880 million to $900 million guidance. U.S. revenue rose 21% to $657.1 million, while international revenue skyrocketed 321% to $233.3 million.
Monthly online revenue per subscriber jumped 30% year over year to $105 per month, while the number of subscribers rose 13% to nearly 2.79 million. However, subscribers did fall by 100,000 sequentially as the company pulled back on the marketing of weight loss drugs.
The company continued to face gross margin pressure in the quarter, with it falling 1,700 basis points year over year to 57%. This was largely due to increased sales of lower-margin branded weight-loss drugs and the scaling of its international business, which carries lower margins.
However, Hims & Hers has been able to leverage its marketing spending, which fell to 28% of revenue from 39% a year ago.
Adjusted EBITDA increased 5% from $78.4 million to $82.4 million. Adjusted earnings per share (EPS) came in at $0.03, down from $0.08 a year ago.
| Metric |
Q3 Results |
Growth (YOY) |
| Revenue |
$890.4 million |
49% |
| Monthly online revenue per subscriber |
$105 |
30% |
| Subscribers |
2.49 million |
13% |
| Adjusted EBITDA |
$82.4 million |
5% |
| EPS |
$0.03 |
(63%) |
| Marketing expense |
$247.3 million |
7% |
| Marketing as % of revenue |
28% |
(1,100 basis points) |
| Gross margin |
74% |
(1,700 basis points) |
Data source: Hims & Hers Health. YOY = year over year.
Time to buy the stock?
Hims & Hers is not without its warts as it navigates increasing sales of lower-margin branded weight-loss drugs while expanding internationally, where margins are also lower. However, the company is still growing its gross profit dollars and leveraging its marketing spend, which should eventually lead to renewed profitability growth.
At the same time, I think the company’s move into peptides could be a huge boost. Peptides show great medical promise, but there isn’t much human testing for some of them, and they have not been approved by the FDA, despite a robust grey market.
From a valuation standpoint, the stock trades at a forward price-to-earnings (P/E ) ratio below 26 based on the analyst consensus for 2027. The company’s expenses are outpacing its peptide opportunity, so I think it should see some nice operating leverage as future sales begin to flow in.
Overall, Hims and Hers remains a high-risk, high-reward stock, but I think this dip could be a nice buying opportunity.
Should you buy stock in Hims & Hers Health right now?
Before you buy stock in Hims & Hers Health, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Hims & Hers Health wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004… if you invested $1,000 at the time of our recommendation, you’d have $338,083!* Or when Nvidia made this list on April 15, 2005… if you invested $1,000 at the time of our recommendation, you’d have $1,021,163!*
Now, it’s worth noting Stock Advisor’s total average return is 830% — a market-crushing outperformance compared to 209% for the S&P 500. Don’t miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of November 13, 2026.
Geoffrey Seiler has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Hims & Hers Health. The Motley Fool has a disclosure policy.