Key Points
-
Higher fuel and insurance claims costs trimmed WM’s margin and left adjusted earnings a few cents short of estimates.
-
Free cash flow rose 20% in the quarter and covered the dividend about 2.6 times over nine months.
-
WM offers a stable dividend with a relatively low yield, but the payout has increased nearly 60% in the last five years.
-
When a stock misses earnings estimates, income investors usually ask one question: Is the dividend safe? For WM (NYSE:WM), the garbage and recycling giant, its latest report suggests the answer is yes — even though the quarter wasn’t perfect.
Third-quarter adjusted earnings per share (EPS) of $2.15 came in a few cents below analyst estimates, and the stock dipped afterward. But the same quarter produced $985 million of free cash flow, about 20% more than a year earlier. If you want dependable income away from AI and tech stocks, the gap between the earnings headline and the cash is worth understanding.
Missed AI’s “Act 1”? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn’t buy Nvidia in 2005. But according to our analysts, we’re only at the end of “Act 1″—the R&D phase. “Act 2” is the global rollout. Continue »
Image source: Getty Images.
What went wrong in the quarter?
Revenue grew 6.3% to $6.85 billion, helped by price increases. Costs were the problem. WM’s adjusted operating margin, a measure of profit before depreciation and similar charges, slipped to 31% from 31.1%. Higher fuel costs and higher risk management costs, WM’s term for insurance and claims, each took about 0.4 percentage points.
The risk management line jumped to $135 million from $72 million. Part of that is a tough comparison, since last year’s quarter benefited from an insurance recovery tied to a 2022 transfer station fire. But this quarter’s figure was also higher than either of the first two. WM recovers some fuel costs through customer surcharges, which brought in $112 million more than a year ago.
How safe is the dividend?
Dividend safety shows up in cash, not quarterly EPS. Free cash flow is the money left after a company pays for the costs of running and maintaining its business. WM generated $3.01 billion through nine months, up from $2.11 billion a year ago. It paid $1.14 billion in dividends over that stretch, so cash flow covered the payout about 2.6 times. Put another way, the dividend used up less than 40% of free cash flow.
Looking ahead, WM expects to pay about $1.5 billion in dividends this year, against free cash flow guidance of $3.75 billion to $3.85 billion. The $3.78 annual rate followed the company’s 23rd straight yearly increase. WM also spent $1.58 billion on buybacks, returning more than 90% of its free cash flow to shareholders.
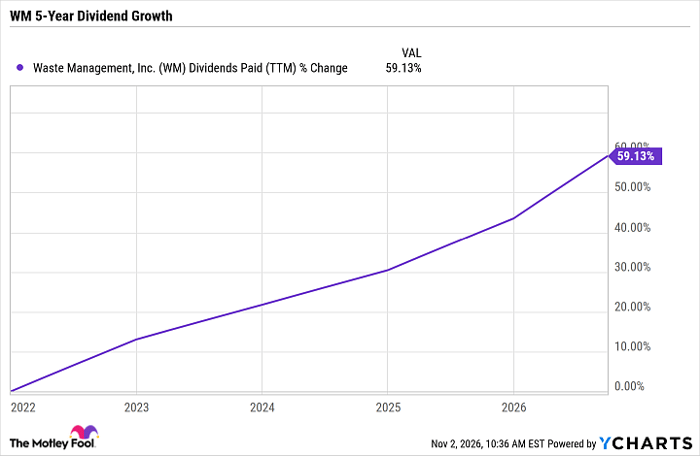
WM Dividends Paid (TTM) data by YCharts
Where could this go wrong?
WM’s volume is slipping. Collection and disposal volume fell 0.4%, partly because WM is shedding lower-margin residential customers. Price increases carried the quarter, and that works until customers push back.
In addition, claims costs could stay high. If risk management expense continues to run near $135 million per quarter, margins will remain under pressure.
Finally, the yield is about 1.6%, which isn’t much current income. But in my view, WM’s appeal lies in growth and consistency, not a large starting payout.
How to play WM stock now
I think WM can be a dependable dividend payer for investors who want income that doesn’t hinge on AI spending, and this quarter reinforced that more than it undermined it. Its cash comes mostly from pricing and picking up trash, not from data center budgets.
The company will likely report earnings for the fourth quarter in late January 2027, so investors should review its risk management costs and free cash flow then and compare them to Q3. If the dividend grows again and claims costs settle down, this earnings miss will look like a blip. If both slip, I’d want to rethink the story.
Should you buy stock in WM right now?
Before you buy stock in WM, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and WM wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004… if you invested $1,000 at the time of our recommendation, you’d have $334,793!* Or when Nvidia made this list on April 15, 2005… if you invested $1,000 at the time of our recommendation, you’d have $1,257,420!*
Now, it’s worth noting Stock Advisor’s total average return is 874% — a market-crushing outperformance compared to 209% for the S&P 500. Don’t miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of November 2, 2026.
Patrick Sanders has no position in any of the stocks mentioned. The Motley Fool recommends WM. The Motley Fool has a disclosure policy.