Key Points
-
On Oct. 14, the Social Security Administration announced a 3.6% cost-of-living adjustment (COLA) for the upcoming year.
-
Trumpflation (inflation driven by President Donald Trump’s policies) has elevated the prevailing inflation rate and, therefore, Social Security’s 2027 COLA.
-
However, larger annual raises are bad news for a retirement program whose asset reserves are an estimated six years away from being depleted.
-
For many of Social Security’s more than 71 million traditional beneficiaries, no announcement is more anticipated than the annual cost-of-living adjustment (COLA) reveal in October.
Social Security’s COLA represents the near-annual “raise” given to beneficiaries to offset inflation (rising prices). For example, if a broad basket of hundreds of goods and services increases in price by 3% from the previous year, Social Security payouts would need to climb by a matching 3% to avoid a loss of buying power. Social Security’s COLA is the tool tasked with keeping benefits on par with inflation.
Missed AI’s “Act 1”? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn’t buy Nvidia in 2005. But according to our analysts, we’re only at the end of “Act 1″—the R&D phase. “Act 2” is the global rollout. Continue »
In 2027, beneficiaries will receive one of their largest raises in the last 35 years, courtesy of President Donald Trump and a few of his policies. Though this “Trump bump” has produced an outsize COLA for the upcoming year, it comes at a potentially steep cost to America’s leading retirement program.
Social Security’s 2027 COLA is one of the largest since 1993
On Oct. 14, after the U.S. Bureau of Labor Statistics released the September inflation report — the final data point needed to calculate Social Security’s COLA for the following year — the Social Security Administration announced that benefits would increase by 3.6% in 2027.
To put this figure into context, only four Social Security COLAs since 1993 have been higher than what was announced a little over two weeks ago:
- 2006: 4.1% COLA
- 2009: 5.8% COLA
- 2022: 5.9% COLA
- 2023: 8.7% COLA (the largest since 1982)
The fifth-largest Social Security COLA in 35 years is expected to increase the average monthly payout for retired-worker beneficiaries by $75 next year. Meanwhile, the average worker with a disability and the average survivor beneficiary should both see their monthly checks climb by about $59.
Furthermore, it marks the sixth consecutive year in which benefits have jumped by at least 2.5%. The last time benefits grew this consistently was 1988 through 1997, when Social Security raises totaled 2.6% to 5.4% each year.
The catalyst behind Social Security’s outsize 2027 raise is Trumpflation (i.e., inflation driven specifically by President Trump’s policies). Two policies, in particular, elevated the prevailing inflation rate and, therefore, Social Security’s 2027 COLA.
Firstly, Trump’s tariff and trade policy has lifted consumer prices in each of the last two years. The president’s “Liberation Day” tariffs provided a Trump bump to Social Security’s 2026 COLA, and his February 2026 temporary duties and recently enacted tariffs under Section 301 of the Trade Act of 1974 are influencing the program’s 2027 COLA.
Adding duties to imported goods increases their price — and if the imported good is unfinished (e.g., steel) and used to complete the manufacture of a product in the U.S., it can raise domestic manufacturing costs, which are then passed on to consumers.
The Trump-led Iran war is the second policy responsible for boosting the inflation rate and Social Security’s 2027 COLA. The eight-month (and counting) closure of the Strait of Hormuz represents the largest energy supply disruption in modern times. Gas and diesel prices have soared in its wake, with evidence mounting that Iran-war-driven inflation has reached the broader U.S. economy.

Image source: Getty Images.
Above-average Social Security raises have consequences
Make no mistake about it: Sizable nominal-dollar increases to Social Security checks are welcome… and necessary to keep up with elevated inflation.
But there’s no free lunch when it comes to Social Security raises. Outsize increases can have potentially devastating consequences for America’s top retirement program.
For more than four decades, the annually released Social Security Board of Trustees Report has warned of a long-term (75-year) unfunded obligation. In easier-to-understand terms, the program’s projected income over the 75 years after the release of a report is estimated to be insufficient to cover outlays, which primarily cover benefits, including COLAs, as well as administrative expenses to oversee the program.
This long-term unfunded obligation hit a staggering $29.3 trillion estimate in the latest Trustees Report.
However, the more pressing issue is the expected depletion of the Old-Age and Survivors Insurance trust fund’s (OASI) asset reserves by the fourth quarter of 2032. The OASI is the trust fund that doles out monthly benefits to retired workers and survivors of deceased workers.
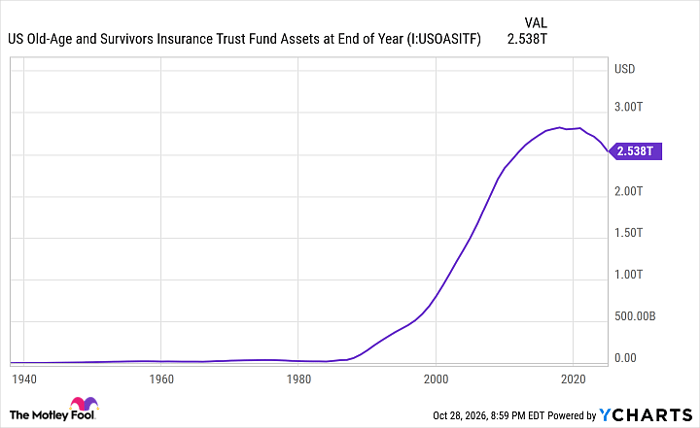
US Old-Age and Survivors Insurance Trust Fund Assets at End of Year data by YCharts
On the one hand, the OASI doesn’t need a dime in its asset reserves to continue making payments. The way Social Security is funded, with the 12.4% payroll tax on earned income generating over 91% of the program’s income, ensures it can’t go bankrupt.
Conversely, if the OASI’s asset reserves are exhausted in six years, as projected, it would confirm that the existing payout scheduling, including COLAs, isn’t sustainable. Sweeping benefit cuts estimated at 22% would be needed to sustain payouts moving forward.
While the Trustees’ OASI solvency estimates remain fluid, they’re based on a laundry list of variables, one of which is the program’s annual cost-of-living adjustment. The Trustees Report assumes modest annual benefit adjustments. However, the fifth-largest COLA over the last 35 years isn’t modest.
The passage of President Trump’s flagship tax and spending law in July 2025, the “Big, Beautiful Bill,” and its negative impact on Social Security already prompted the Trustees to shift the OASI’s projected asset reserve depletion date from the first quarter of 2033 to the fourth quarter of 2032 in the latest report.
A second consecutive year with a Trump bump and an above-average COLA threatens to drain the OASI’s asset reserves even quicker than estimated. In other words, the timeline to a 22% (or greater) sweeping benefit cut for retired workers and survivors of deceased workers may be less than six years.
The $23,760 Social Security bonus most retirees completely overlook
If you’re like most Americans, you’re a few years (or more) behind on your retirement savings. But a handful of little-known “Social Security secrets” could help ensure a boost in your retirement income.
One easy trick could pay you as much as $23,760 more… each year! Once you learn how to maximize your Social Security benefits, we think you could retire confidently with the peace of mind we’re all after. Join Stock Advisor to learn more about these strategies.
View the “Social Security secrets” »
The Motley Fool has a disclosure policy.