Key Points
-
Rivian’s deliveries jumped from the second to third quarters, but its automotive gross profit didn’t follow.
-
Currently, Rivian is absorbing large upfront launch costs without the benefit of second and third shifts improving production efficiency yet.
-
Rivian’s automotive gross profit has much potential upside over the next 18 months as the company adds shifts and realizes more production efficiency.
-
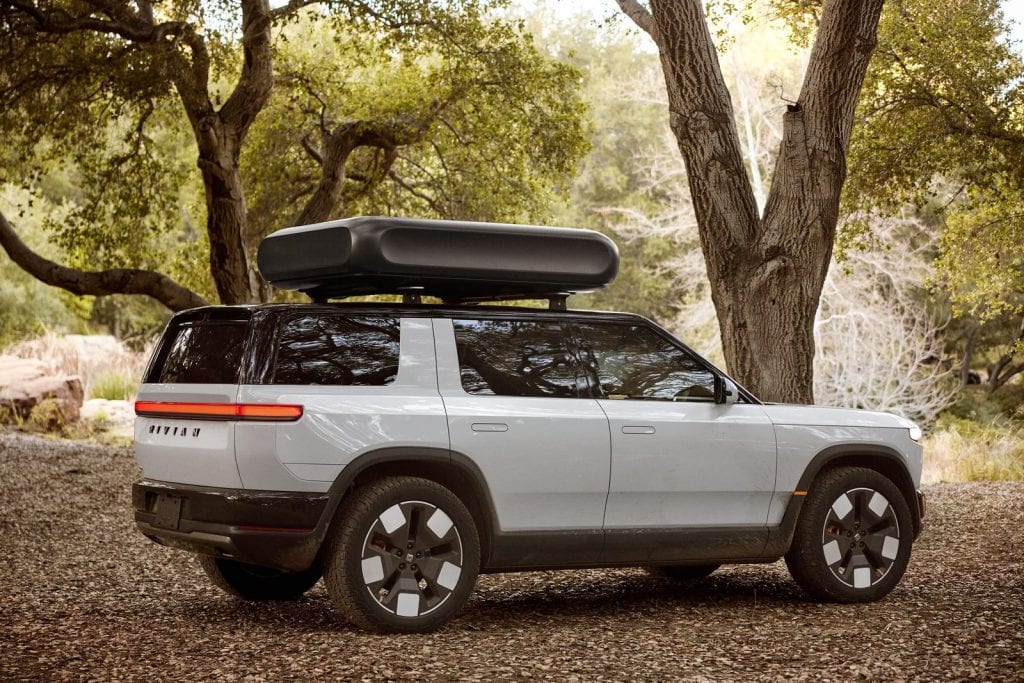
Rivian Automotive (NASDAQ: RIVN) investors have a sales surge worth smiling about. Third-quarter deliveries reached 19,248 vehicles, jumping roughly 58% from the second quarter as R2 became the company’s best-selling vehicle. Then comes a bit of a head-scratcher: Companywide gross profit remained mostly flat over that same stretch, with deteriorating automotive gross profit offsetting growth in its software & services segment — keep in mind Rivian had been making consistent progress on companywide gross profitability since 2023.
Rivian produced and delivered more vehicles in Q3, but had essentially the same gross profit and a noticeable decline in automotive gross profit. Before investors throw something at their screens, there are certainly moving pieces worth understanding.
Missed AI’s “Act 1”? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn’t buy Nvidia in 2005. But according to our analysts, we’re only at the end of “Act 1″—the R&D phase. “Act 2” is the global rollout. Continue »
Two businesses, different directions
Rivian’s software and services business generated $256 million in third-quarter gross profit, up from $215 million in the second quarter. Meanwhile, the automotive gross loss widened from $36 million to $80 million, swallowing that improvement.
Software deserves credit for helping support the business early and significantly. But investors buying into the R2 growth story also need to see progress in profitably manufacturing vehicles. Higher production can still improve efficiency, even when other costs outweigh those gains. Two headwinds help explain what happened this quarter.
Credit revenue
First, regulatory-credit revenue fell from $106 million in the second quarter to $81 million in the third quarter, a decline of roughly 24%. Credits still provided a substantial benefit, but a smaller one, and one that management previously expected “substantially” less support from during the second half of 2026.
Subtracting that revenue from reported automotive gross profit gives an illustrative loss of $142 million in Q2 versus $161 million in Q3. That’s a $19 million deterioration, smaller than the reported $44 million increase in automotive gross losses. These calculations leave other benefits and expenses intact; they just help give a slightly clearer picture of its automotive gross profit in a scenario where credit revenue becomes a nonfactor.
Bigger launch bill
Second, Rivian recognized approximately $120 million in incremental R2 ramp costs, compared with roughly $100 million in Q2. Both figures measure costs relative to more normalized production levels. The entire $120 million wasn’t a new expense suddenly appearing this quarter.
Rivian explains that ramping up R2 can lead to higher costs while factory capacity remains underused. More production can improve efficiency without immediately overcoming those launch expenses. If you’re asking yourself how that works, good question. Part of that $120 million includes expenses such as expedited freight, while factory overhead is still spread across fewer vehicles than the planned two-shift operation could produce. Getting production running smoothly takes time — and the savings/efficiencies don’t arrive immediately.
There’s another complication: Tariff-refund receivables benefited automotive results in both quarters, but we don’t have specific information to know which quarter it benefited more. In other words, Rivian’s sales are accelerating, but launch costs and fluctuating benefits make its automotive gross profit progress harder to gauge.
What investors should watch
Rivian has delivery momentum. Now investors need to see its expanding production shifts and easing launch costs translate into sustained automotive gross profit, especially if regulatory credits and tariff-related benefits provide less support.
Software is doing its part, but its contribution can obscure what’s happening in the factory. Watching the two businesses separately will help investors judge whether R2 is delivering the financial progress they’re counting on. Keep in mind that in the near term, there’s likely more improvement upside in Rivian’s automotive segment, and realizing those gains will be a big step on its drive to reach breakeven and, eventually, bottom-line profits.
Don’t let one complicated quarter spoil the delivery celebration. Just remember that selling more vehicles is the beginning of the payoff, not the finish line. Rivian still needs to show it can consistently make money building them over the next year.
Should you buy stock in Rivian Automotive right now?
Before you buy stock in Rivian Automotive, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Rivian Automotive wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004… if you invested $1,000 at the time of our recommendation, you’d have $344,878!* Or when Nvidia made this list on April 15, 2005… if you invested $1,000 at the time of our recommendation, you’d have $1,097,846!*
Now, it’s worth noting Stock Advisor’s total average return is 852% — a market-crushing outperformance compared to 208% for the S&P 500. Don’t miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of November 10, 2026.
Daniel Miller has no position in any of the stocks mentioned. The Motley Fool has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy.