Key Points
-
Rocket Lab shares are around 70% below their May record close.
-
The company’s second-quarter adjusted EBITDA loss narrowed to $8.8 million.
-
Management expects a wider adjusted EBITDA loss for the third quarter.
-
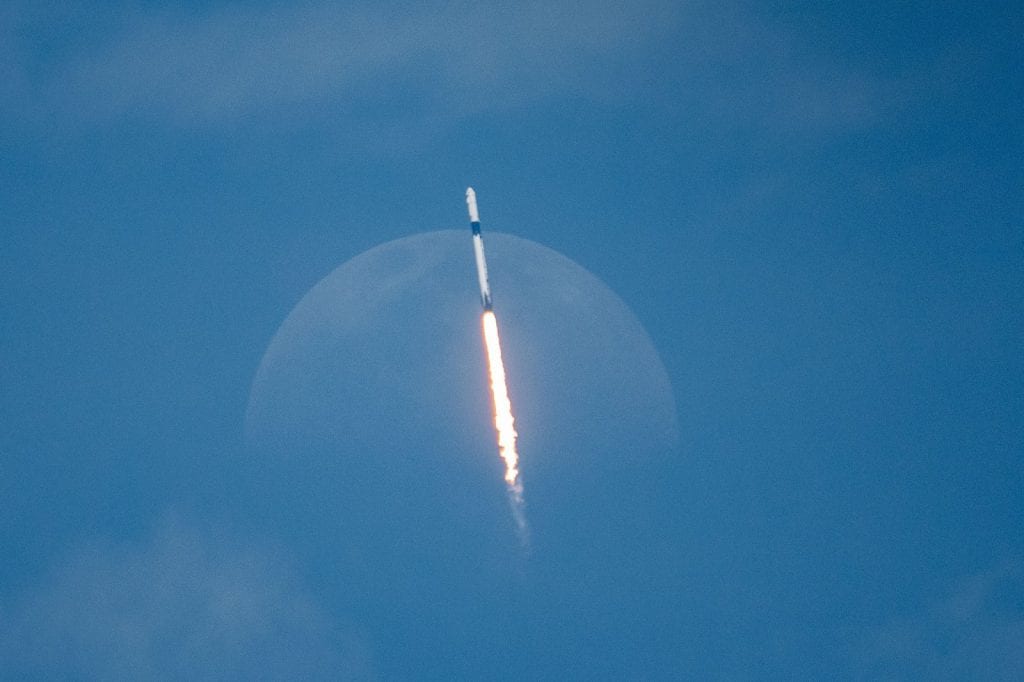
Rocket Lab (NASDAQ:RKLB) stock had another tough day on Thursday. Shares dropped as much as 16% in the session and were roughly $46 as of this writing, while much of the tech sector sold off with them. The space stock closed at a record high of $150.23 on May 27, so it’s now about 70% below its peak.
When I last covered Rocket Lab in late October, shares were near $58, and I wasn’t willing to buy the growth stock there. The stock’s now about 20% cheaper, and the company reports third-quarter results after the close on Monday, Nov. 9.
Missed AI’s “Act 1”? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn’t buy Nvidia in 2005. But according to our analysts, we’re only at the end of “Act 1″—the R&D phase. “Act 2” is the global rollout. Continue »
Is the stock finally a buy at this level?
Image source: Getty Images.
A lower price tag
Including the preferred stock that converts into common shares, Rocket Lab is now worth about $31 billion. Management forecast third-quarter revenue of $250 million to $265 million, which would be 61% to 71% above the $155 million it pulled in during the third quarter of 2025.
Annualizing the midpoint of that range, the stock trades at around 30 times sales. At $58, it traded at closer to 38 times sales. In other words, every dollar of Rocket Lab’s revenue costs investors much less now than it did just a few weeks ago.
And revenue growth hasn’t been the issue. Rocket Lab has set a revenue record every quarter of 2026 so far. Sales hit $200 million in the first quarter and then $234 million in the second, up 62% year over year.
Showing how strong demand is, Rocket Lab finished June with a record backlog (the value of signed contracts it hasn’t booked as revenue yet) of $2.36 billion. It’s more than twice the year-ago figure.
Still, a valuation of 30 times sales assumes years of fast growth. And it arguably assumes lots of success for Neutron, the reusable medium-lift rocket Rocket Lab is developing for satellite constellation launches and national security missions.
When will Neutron fly?
In mid-October, Rocket Lab pushed Neutron’s first launch to 2027. The company found air pockets between the carbon-fiber layers of a dome for the rocket’s first-stage propellant tank, and it’s making a replacement. Earlier this year, it had already shifted the debut from early 2026 to late 2026.
Rocket Lab hasn’t named a new target date. It plans to pick one after testing that it expects to finish in the first quarter of 2027.
Monday’s report likely won’t say much about Neutron’s timing, other than showing if that testing is on track. Until then, investors have to judge the stock by the business Rocket Lab already runs.
Losses are about to grow again
Rocket Lab has made strong progress toward profitability. Its adjusted EBITDA (earnings before interest, taxes, depreciation, and amortization) loss fell to $8.8 million in the second quarter of 2026, down from $27.6 million the year before. Over the whole first half of the year, the adjusted EBITDA loss was $20.6 million, compared with $57.5 million in the first half of 2025. Its bottom-line net loss narrowed too, to $49 million in the second quarter from $66 million in the year-ago period. And this progress came even while Neutron development helped drive research and development spending up 25% year over year.
But management’s third-quarter forecast calls for an adjusted EBITDA loss of $17 million to $23 million. At the midpoint, the company would lose about as much in one quarter as it did in the entire first half.
Part of the reason is a lower expected gross margin. Management expects its non-GAAP (adjusted) gross margin to fall to between 35% and 37% in the third quarter, down from 41.5% in the second.
Sure, Rocket Lab could come in better than its own range. But even the $17 million end of it would be almost double the second-quarter loss — when the stock has little room for disappointment.
I think the lower price helps, but it doesn’t change what Rocket Lab needs to prove. At around 30 times sales, the stock is closer to a price I’d consider paying than it has been at any point this fall.
But the two questions that matter most aren’t settled yet. Neutron still has no launch date, and the loss trend is about to reverse, at least for a quarter. With the report just four days away, waiting for it seems to cost a buyer very little.
If the third-quarter loss comes in close to the better end of guidance and Neutron’s testing stays on track, I’d consider a small stake after the report. Until then, I’m happy to wait.
Missed AI’s “Act 1”? Act 2 Could Be 14x Bigger
Most investors think they missed the AI boat because they didn’t buy Nvidia in 2005.
But according to our analysts, we’re only at the end of “Act 1″—the R&D phase. “Act 2” is the global rollout, a massive technology build-out that Google’s CEO says could be more profound than fire or electricity.
While everyone watches the chip designers, one “backbone” company provides the critical technology that Nvidia and AMD literally cannot function without. We’ve detailed this under-the-radar player in our new AI Playbook.
Continue »
Daniel Sparks and his clients do not have positions in any of the stocks mentioned. The Motley Fool has positions in and recommends Rocket Lab. The Motley Fool has a disclosure policy.