Key Points
-
Walmart continues to grow in a challenging macro environment.
-
Its stock looks expensive, but it deserves that premium valuation.
-
Walmart‘s (NASDAQ: WMT) stock closed at an all-time high of $133.88 on May 19, 2026. That marked a 238% gain over its previous four years. It’s only pulled back about 3% to $130 as of this writing, but I think it’s still a great stock to buy today and hold for the next decade.
Why is Walmart’s business so resilient?
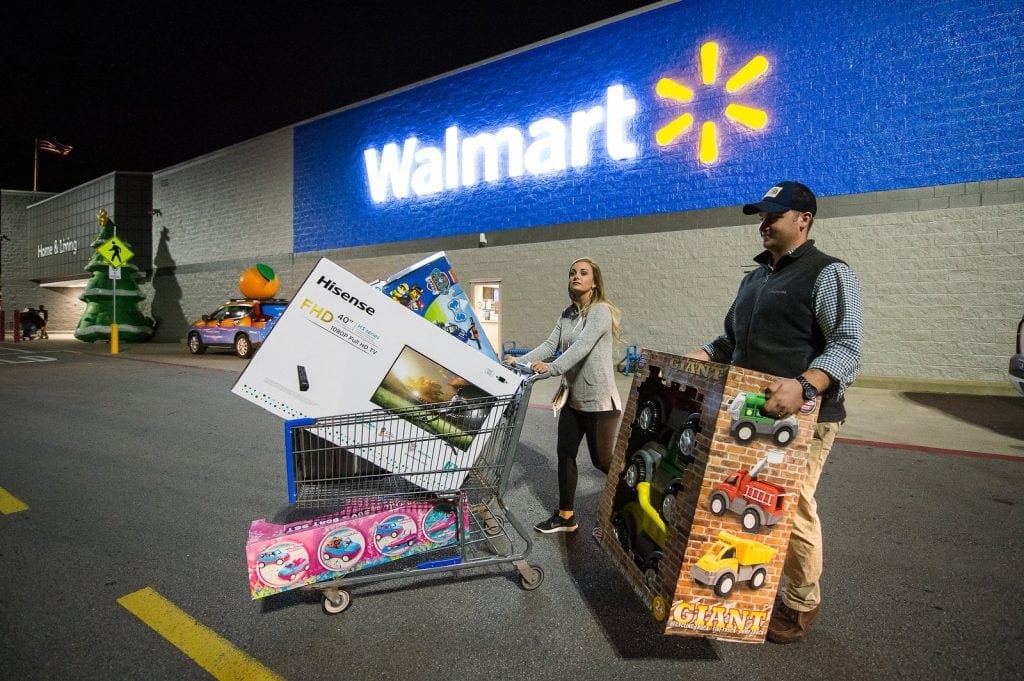
Walmart operates more than 10,900 stores and warehouse clubs across 19 countries, as well as e-commerce websites and smaller regional banners in overseas markets.That scale enables it to sell its products at lower margins than smaller retailers, and it uses its brick-and-mortar stores to fulfill online orders, helping it keep pace with Amazon (NASDAQ: AMZN) and other e-tailers.
Walmart also locks in its shoppers with private-label products, its shopping app, and its Walmart+ subscription service, which offers discounts, free shipping, streaming media, and other perks. It’s also using AI to upgrade its logistics and inventory management capabilities.
How fast is Walmart growing?
From fiscal 2022 to fiscal 2026 (which ended this January), Walmart’s revenue and adjusted EPS grew at CAGRs of 5.6% and 5.3%, respectively. Its core U.S. business — which accounts for most of its revenue — grew steadily even as inflation, tariffs, geopolitical conflicts, and other macro headwinds rattled the global economy and throttled consumer spending. It also stabilized its international segment after divesting some of its weaker assets in fiscal 2022.
|
Metric
|
FY 2022
|
FY 2023
|
FY 2024
|
FY 2025
|
FY 2026
|
|
Walmart U.S. Comps Growth
|
6.4%
|
6.6%
|
5.6%
|
4.5%
|
4.6%
|
|
Sam’s Club U.S. Comps Growth
|
9.8%
|
10.5%
|
4.8%
|
5.9%
|
5%
|
|
Walmart International Sales Growth
|
(16.8%)
|
0%
|
10.6%
|
6.3%
|
7%
|
|
Net Sales Growth
|
2.4%
|
6.7%
|
6%
|
5.1%
|
4.7%
|
|
Adjusted EPS Growth
|
17.9%
|
(2.6%)
|
5.7%
|
9%
|
9.1%
|
Data source: Walmart. Comps growth excludes fuel sales.
From fiscal 2026 to fiscal 2029, analysts expect Walmart’s net sales and adjusted EPS to grow at CAGRs of 5% and 11%, respectively. At $130, it might seem pricey at 40 times next year’s earnings, but its scale, steady growth, and wide moat justify that higher valuation.
Why is Walmart a great long-term play?
In the near term, Walmart’s stock could remain under pressure as sticky inflation, elevated interest rates, and high Treasury yields drive investors toward more conservative investments.
But over the long term, Walmart will remain an evergreen investment and a “best-in-breed” play on the brick-and-mortar retail and e-commerce markets. That’s why I’d still buy Walmart’s stock today — even though it’s only trading slightly below its all-time high.
Should you buy stock in Walmart right now?
Before you buy stock in Walmart, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Walmart wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004… if you invested $1,000 at the time of our recommendation, you’d have $342,020!* Or when Nvidia made this list on April 15, 2005… if you invested $1,000 at the time of our recommendation, you’d have $1,270,017!*
Now, it’s worth noting Stock Advisor’s total average return is 885% — a market-crushing outperformance compared to 208% for the S&P 500. Don’t miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of November 4, 2026.
Leo Sun has positions in Amazon. The Motley Fool has positions in and recommends Amazon and Walmart. The Motley Fool has a disclosure policy.