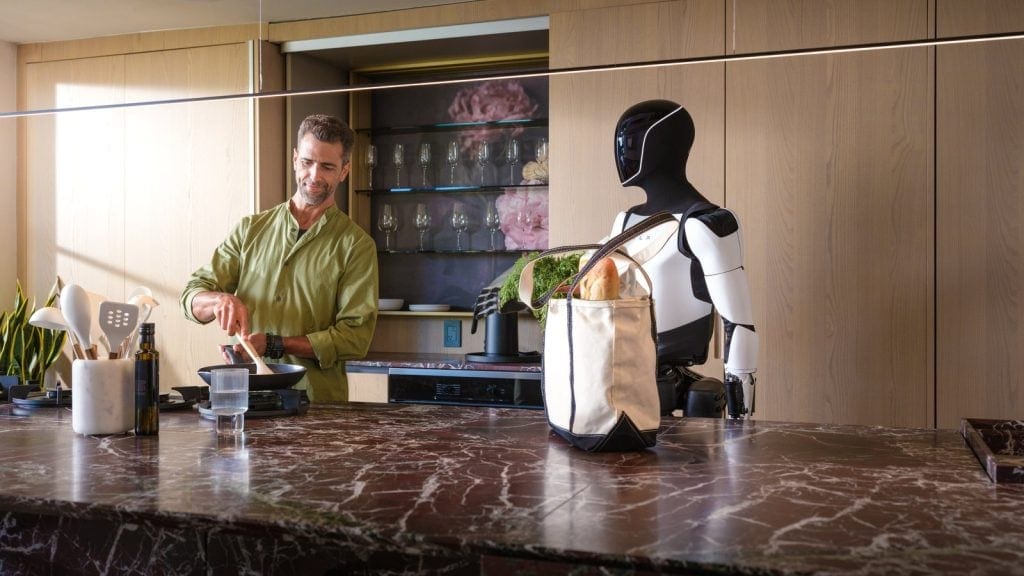
Tesla (NASDAQ: TSLA) aims to produce up to one million Optimus robots in 2027. To achieve that ambitious goal, it plans to ramp up its production to 20,000 units per week.
That’s great news for Tesla’s suppliers, but one hot chipmaker that was left out of the loop was Nvidia (NASDAQ: NVDA). Instead of using Nvidia’s AI chips, the Optimus uses Tesla’s own custom Full Self-Driving (FSD) inference chips. But Texas Instruments (NASDAQ: TXN), which doesn’t get as much attention as Nvidia, actually produces components for the Optimus.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a “Double Down” signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same “Total Conviction” signal is flashing for a company 1/100th the size of Nvidia. Continue »
What does Texas Instruments produce for Optimus?
TI has been one of Tesla’s main suppliers of automotive chips for over a decade. It produces power, driver, and signal-chain components rather than high-end AI processors.
Optimus uses over 40 servo motors in its hands, arms, knees, and ankles. TI produces the isolated gate drivers and integrated motor controllers that deliver precise currents to those actuators. It also produces high-resolution analog-to-digital converters (ADCs) for processing continuous data from its force and torque sensors, optical encoders, and tactile fingertips.
TI supplies the power management chips that regulate the power flowing from the Optimus’ 2.3 kWh central battery pack to its internal sensors, logic boards, and processing units. Its battery monitor ICs and cell-balancing chips also continuously monitor the thermal state, current output, and voltage for each cell within the battery pack.
How much revenue could TI generate from Optimus?
If Tesla produces a million Optimus units per year, it could translate to $250 million to $500 million in annual revenue for TI’s analog business. That estimate, based on early industry teardowns, assumes TI sells $250-$500 worth of components per Optimus.
In 2025, TI’s analog revenue rose 15% year over year to $14 billion, or 79% of its total revenue of $17.7 billion. In the first nine months of 2026, its analog revenue rose 27% year over year to $13.2 billion, or 81% of its total revenue of $16.3 billion. TI’s total revenue rose 13% in 2025, and another 23% year over year in the first nine months of 2026.
That acceleration was driven by the rapid expansion of the AI and data center markets, which boosted its sales of power distribution, voltage regulation, and high-speed signal chips; the industrial sector’s recovery; and a growing number of chips per vehicle in the auto sector.
If Tesla actually ramps up its Optimus production to 20,000 units per week, it could become another catalyst for that booming business. That expansion would also boost its margins and profits, since its analog chips are much cheaper to produce than its embedded processing chips, which account for a much smaller percentage of its revenue and operating profits.
According to Fortune Business Insights, the humanoid robot market could expand at a 50.6% CAGR from 2026 to 2034. TI will likely profit from the market’s expansion as it provides chips and components to a broader range of robot builders.
How does the Optimus highlight TI’s core strengths?
TI doesn’t generate as much excitement as top AI chipmakers like Nvidia or Broadcom, but it provides essential chips for a wide range of industries. So even though it’s benefiting from the AI boom, its sales won’t drop off a cliff if AI spending slows down.
From 2025 to 2028, analysts expect TI’s revenue and EPS to grow at CAGRs of 18% and 35%, respectively. Its stock still looks reasonably valued at 27 times next year’s earnings, and it pays a forward dividend yield of nearly 2%. If you’re looking for a balanced, well-diversified chipmaker that is also exposed to the higher-growth AI and robotics markets, TI checks all the right boxes.
Missed AI’s “Act 1”? Act 2 Could Be 14x Bigger
Most investors think they missed the AI boat because they didn’t buy Nvidia in 2005.
But according to our analysts, we’re only at the end of “Act 1″—the R&D phase. “Act 2” is the global rollout, a massive technology build-out that Google’s CEO says could be more profound than fire or electricity.
While everyone watches the chip designers, one “backbone” company provides the critical technology that Nvidia and AMD literally cannot function without. We’ve detailed this under-the-radar player in our new AI Playbook.
Continue »
Leo Sun has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Broadcom, Nvidia, Tesla, and Texas Instruments. The Motley Fool has a disclosure policy.