Key Points
-
Enterprise Products Partners has raised its dividend for 28 straight years.
-
The company has seen its shares jump up over 19% so far this year.
-
It’s also in the middle of a $5 billion share buyback program.
-
One of the main reasons investors buy Enterprise Products Partners (NYSE: EPD) stock is its distributions to investors, amounting to a dividend yield of 5.78% at its current share price. That’s five times what the average S&P 500 stock’s dividend yields.
If there’s one concern about the Enterprise’s dividend, it’s that its increases are getting smaller. The midstream operator raised its total distributions by only 2.7% this year. In 2025, the distributions increased by 3.8%. In 2024, the dividend increase was 5%.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a “Double Down” signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same “Total Conviction” signal is flashing for a company 1/100th the size of Nvidia. Continue »
The downward trend might be cause for alarm for some, but there are three reasons why investors shouldn’t worry.
The stock continues to be shareholder-friendly
The distribution coverage ratio is actually improving, which means the dividend is safer than before. In the third quarter, the company reported operational distributable cash flow (DCF) of $2.3 billion, up 27% from the same quarter a year ago. That means DCF coverage is 1.9x, up from 1.5x in the third quarter of the prior year.
The company’s DCF payout ratio over the past 12 months is 54%, down from 58% in the same period a year ago, meaning the distribution increases should continue. The company’s dividend track record speaks volumes as it has raised its dividend for 28 consecutive years.
While its increases have been smaller as of late, the energy company has increased its stock buybacks, which helps buoy the stock’s price. It is in the midst of a multi-year $5 billion stock repurchase program.
Its core business remains strong
The stock is up about 19% so far this year because of consistently strong financials. In the third quarter, Enterprise reported earnings per share (EPS) of $0.75, up 21% year over year, while adjusted earnings before interest, taxes, depreciation, and amortization (EBITDA) were $2.8 billion, up 16% over the same quarter a year ago. Adjusted core funds from operations were $2.4 billion, up 18% year over year.
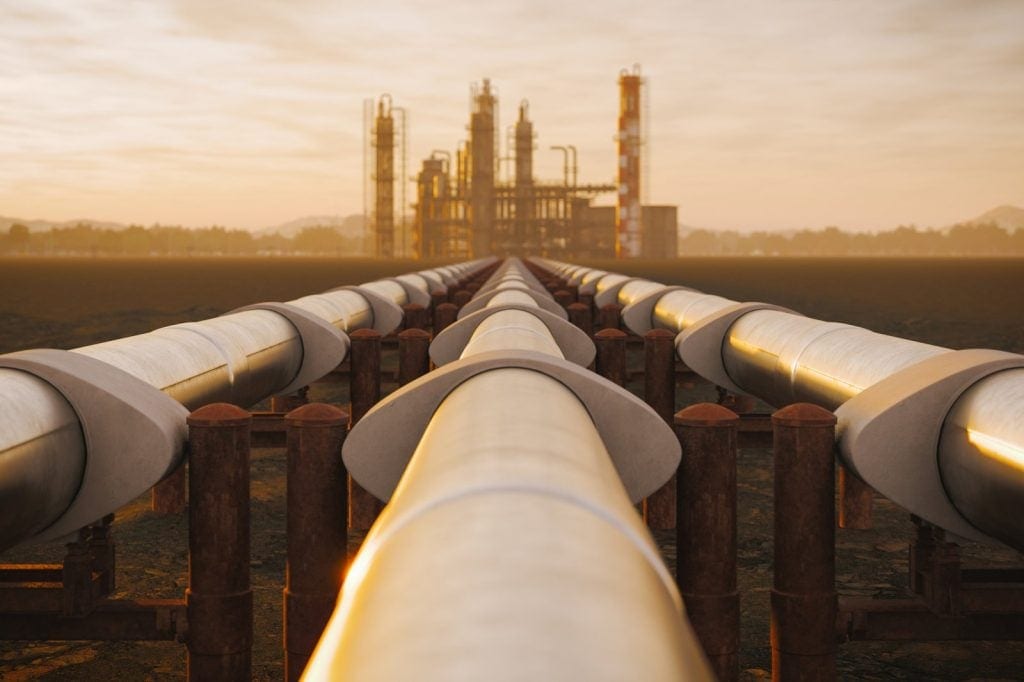
The midstream operator charges customers a toll-like fee to use its more than 50,000 miles of pipelines and additional storage facilities, so the company isn’t affected by short-term oil or gas price changes.
Enterprise controls an interconnected asset base across North America, stretching from gathering systems in the Permian Basin to large-scale export facilities on the U.S. Gulf Coast. This setup allows it to capture revenue across multiple stages of the energy value chain. The company reported record third-quarter volumes at its Permian Basin natural gas processing plants, natural gas liquids pipelines, and ethane marine export terminals.
The stock remains a bargain
Compared with its midstream competitors, Enterprise’s shares are relatively inexpensive, with a valuation of less than 17 times trailing earnings and less than 13 times forward earnings. The company’s recent lack of large distribution raises, rather than being a red flag, is just another sign of a conservative company that is looking to grow without going heavily into debt.
Enterprise consistently deploys $2 billion-$3 billion annually into organic expansion projects, such as new Permian gas processing plants and NGL fractionators, while maintaining an investment-grade balance sheet. As of the third quarter, it had a 3.0 leverage ratio, right in the middle of the company’s target range of 2.75x to 3.25x.
Should you buy stock in Enterprise Products Partners right now?
Before you buy stock in Enterprise Products Partners, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Enterprise Products Partners wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004… if you invested $1,000 at the time of our recommendation, you’d have $342,020!* Or when Nvidia made this list on April 15, 2005… if you invested $1,000 at the time of our recommendation, you’d have $1,270,017!*
Now, it’s worth noting Stock Advisor’s total average return is 885% — a market-crushing outperformance compared to 208% for the S&P 500. Don’t miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of November 4, 2026.
James Halley has no position in any of the stocks mentioned. The Motley Fool recommends Enterprise Products Partners. The Motley Fool has a disclosure policy.