Key Points
-
Amazon is on track to spend $220 billion on the AI build-out this year.
-
The company just reported negative free cash flow for the trailing 12 months, due to its heavy AI investments.
-
Artificial intelligence (AI) stocks have been driving stock market performance in recent years, and investors have cheered growth in the space. But to keep this growth story going, tech giants have to invest heavily, and that’s exactly what they’ve been doing over the past several quarters. This investment, totaling hundreds of billions of dollars, has gone into the infrastructure build-out, with cloud players and other “hyperscalers” building data centers and furnishing them with equipment.
Amazon (NASDAQ:AMZN), as the owner of Amazon Web Services (AWS), is one of these players. This week, the company reported earnings that fell short of estimates, and negative free cash flow was also deeper than expected. On top of this, Amazon says it aims to “spend meaningfully more” next year.
Missed AI’s “Act 1”? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn’t buy Nvidia in 2005. But according to our analysts, we’re only at the end of “Act 1″—the R&D phase. “Act 2” is the global rollout. Continue »
The news sent the stock lower in the following trading session, and this is after Amazon’s 14% drop from a high back in August. Now, here’s why this player is a once-in-a-decade buy hiding in plain sight.
Image source: Getty Images.
Amazon’s e-commerce dominance
So, first, let’s catch up on the Amazon story so far and its presence in AI. This company is probably best known for its e-commerce business, as many of us shop on Amazon daily for groceries and other essentials or turn to the platform for entertainment in the form of books and movies. The Prime subscription program, offering fast delivery and other perks, has kept customers loyal and the revenue engine going.
Meanwhile, AWS has become the company’s main profit driver over the years — and now, the AI opportunity is supercharging growth. AWS is the world’s No. 1 cloud services provider, making it the natural choice for customers that already use the platform for non-AI services. For AI, they come to AWS for any of their needs, from AI chips to large language models and agentic AI.
Due to this, AWS has delivered explosive growth in recent quarters, and performance in the third quarter extended this trend. The cloud unit reported 39% revenue growth to $46 billion, beating analysts’ estimates.
However, to generate such growth today and into the future, Amazon has prioritized investing in the AI build-out. During the latest quarterly report, the company kept its capital spending forecast for the year at $220 billion, but as I mentioned above, it said it will keep up the aggressive spending next year. Amazon reported negative free cash flow of $42 billion in the trailing 12 months as it paid for property and equipment.
Concern about the future AI revenue opportunity
Investors are happy to see AI growth, but in recent months, they’ve started to worry that the revenue opportunity may not justify such spending levels. As a result, they’ve grown more cautious about AI stocks, particularly the cloud giants like Amazon that are leading the infrastructure ramp-up.
This has weighed on Amazon stock, but I think the concerns may be overdone. Here’s why Amazon stock today may be a once-in-a-decade buying opportunity. And it starts with what Amazon chief Andy Jassy said this week after announcing his plans for more AI spending.
Jassy said Amazon, as it increases spending, is seeing “a clear line of sight to attractive financial returns” and that even a $184 billion annual run rate at AWS leaves plenty of room for growth. In fact, based on Amazon’s innovation, additional capacity to come, and demand from customers, Jassy predicts that AWS can become a trillion-dollar revenue business within the coming five to 10 years.
If he’s right, spending heavily today is clearly the right move. The strength of demand so far and the fact that AI usage is in its early stages give us reason to be optimistic about what’s to come. Meanwhile, Amazon stock trades at 30x forward earnings estimates.
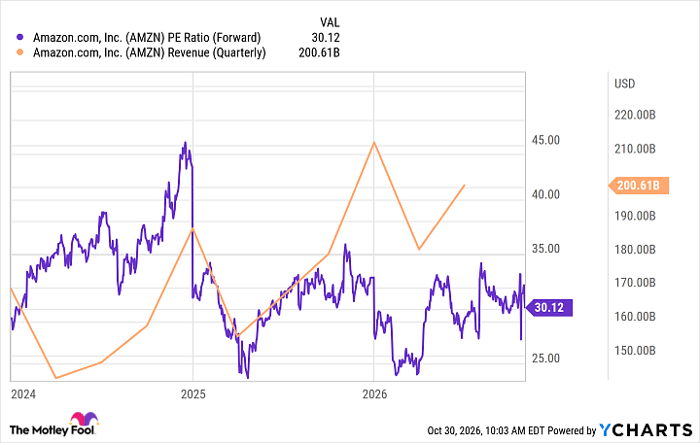
AMZN PE Ratio (Forward) data by YCharts
This isn’t its lowest ever, but Amazon is reasonably priced considering today’s revenue levels and the strength of growth.
Of course, the path may not be completely linear, and the AI story could encounter some turbulence at certain points. As it stands, Amazon has said pressure on free cash flow would continue during this AI build-out phase. While some may hesitate to buy Amazon because of these concerns, I say the positives outweigh the negatives — and that makes the stock a once-in-a-decade buy hiding in plain sight.
Should you buy stock in Amazon right now?
Before you buy stock in Amazon, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Amazon wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004… if you invested $1,000 at the time of our recommendation, you’d have $334,631!* Or when Nvidia made this list on April 15, 2005… if you invested $1,000 at the time of our recommendation, you’d have $1,312,844!*
Now, it’s worth noting Stock Advisor’s total average return is 893% — a market-crushing outperformance compared to 213% for the S&P 500. Don’t miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of October 31, 2026.
Adria Cimino has positions in Amazon. The Motley Fool has positions in and recommends Amazon. The Motley Fool has a disclosure policy.