Key Points
-
Vistra stock has fallen 20% this year as regulatory scrutiny and concerns over electricity costs weigh on independent power producers.
-
Agreements with Meta and Amazon Web Services fund capacity upgrades while helping Vistra secure long-term cash flow.
-
Nearly all of Vistra’s 2027 power capacity is hedged, and management recently increased its share repurchase program by $1.5 billion.
-
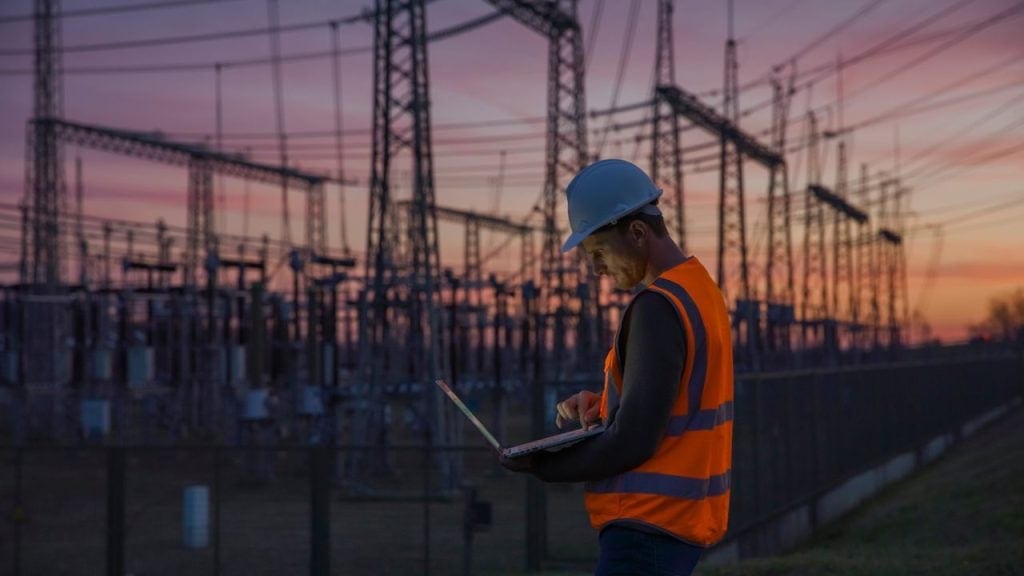
Vistra (NYSE:VST) stock was swept up in the artificial intelligence (AI) sell-off in November, but its decline began well before this month’s midterm elections. Power producers have faced regulatory scrutiny over rising consumer electricity prices and who foots the bill for data centers’ growing energy demands.
With the market weighing the AI data center build-out narrative, Vistra’s beaten-down stock is worth buying the dip on before November ends. Here’s why.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a “Double Down” signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same “Total Conviction” signal is flashing for a company 1/100th the size of Nvidia. Continue »
Image source: Getty Images.
Vistra has had a tough year as regulators scrutinize deals
After a strong performance in 2025, Vistra stock has fallen 20% this year. Regulators across major data center hubs have pushed back on electricity deals to ensure ratepayers don’t end up paying for higher costs and grid expansions.
Midterm election results, notably in Texas, cast a shadow over the ongoing data center build-out. That said, outgoing Governor Greg Abbott had already paused permits and ERCOT approvals while the grid operator audited grid impacts. Not only that, but evolving rules requiring data centers to bring their own energy favor Vistra, which is contracting directly with hyperscalers while adding capacity.
Vistra has reached agreements with Meta Platforms and Amazon Web Services, and under these power purchase agreements, the hyperscalers are funding capacity uprates, addressing one of the biggest concerns while Vistra locks in long-term cash flow.
Here’s why Vistra stock is a buy in November
Management forecasts adjusted EBITDA of $7.7 billion to $8.5 billion, and most of its 2027 capacity is already hedged, protecting near-term cash flows. The stock is down, and Vistra’s management announced it would add another $1.5 billion to its share repurchase program, capitalizing on the beaten-down stock.
For investors bullish on long-term power demand from data centers, Vistra stock is quite appealing at today’s price, now trading at just 13 times its forecasted 2027 earnings.
Should you buy stock in Vistra right now?
Before you buy stock in Vistra, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Vistra wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004… if you invested $1,000 at the time of our recommendation, you’d have $305,941!* Or when Nvidia made this list on April 15, 2005… if you invested $1,000 at the time of our recommendation, you’d have $771,325!*
Now, it’s worth noting Stock Advisor’s total average return is 719% — a market-crushing outperformance compared to 192% for the S&P 500. Don’t miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of November 21, 2026.
Courtney Carlsen has positions in Meta Platforms and Vistra. The Motley Fool has positions in and recommends Amazon, Meta Platforms, and Vistra. The Motley Fool has a disclosure policy.