Anthropic is planning to go public on Nov. 19 and is targeting a starting price range of $70 to $78 per share. At the high end of that range, Anthropic would be worth about $1.4 trillion. That’s a lot less than the $2 trillion valuation it was seeking not too long ago, but with the shift in sentiment regarding AI investing, this aligns with what the broader market is experiencing.
Final pricing will be set a day or two before going public, and unless investors have access to IPO pricing (some brokerages are offering this to certain investors), they may have to pay a different price than what Anthropic is seeking.
Missed AI’s “Act 1”? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn’t buy Nvidia in 2005. But according to our analysts, we’re only at the end of “Act 1″—the R&D phase. “Act 2” is the global rollout. Continue »
But my question today is: Is Anthropic a buy at the estimated $70-$78 price tag?
Image source: Getty Images.
Anthropic’s business is impressive
Anthropic is unlike any company that investors have ever seen go public. While Space Exploration Technologies (NASDAQ:SPCX) holds the record for the largest IPO in history, its growth rates looked nothing like Anthropic’s.
Anthropic is one of the two primary AI labs, the other being OpenAI. It makes the Claude AI model, which has emerged as one of the best options available. It has grown rapidly as a result, with its revenue during the first six months of the year rising 1,305%. That’s simply incredible, and few companies that investors have ever looked at have been able to grow that quickly.
However, revenue growth isn’t the only part of a business.
During those six months, Anthropic’s net loss totaled $80 billion on a revenue base of $16.3 billion. That’s a major mismatch, and investors have every right to be concerned about those losses. However, investors need to understand why it was losing so much money.
The reality is that $72.4 billion of its $80 billion loss had to do with its valuation rising. Essentially, Anthropic issued shares in exchange for funding, and as the value of those shares rose, it turned into a loss for the company. So, this is mostly an accounting artifact.
The better way to assess Anthropic’s profitability (or lack thereof) is its operating margin. During the first six months of the year, Anthropic lost just under $700 million. So, operational profitability should be right around the corner. That’s great news for investors, and it eases some concerns that I would have about the long-term viability of the business.
But is it actually a smart buy at the estimated starting price tag?
Anthropic’s valuation is actually reasonable
Let’s say that the stock starts trading at $70 per share, and spikes to $78 per share due to Day 1 investor interest, which would only be an 11% jump. At a $1.4 trillion valuation, Anthropic would be one of the largest stocks on the market. But is that an inflated valuation, or is it just right?
Over the first nine months of the year, Anthropic generated $33.2 billion. During the first six months, that figure was $16.3 billion. So the six-month figure doubled over the next three months. If it can double the nine-month figure and get to annual revenue of $66 billion, a $1.4 trillion valuation would price the stock at 21 times that number, which would make it far cheaper than SpaceX is right now, which is trading around 57 times sales.
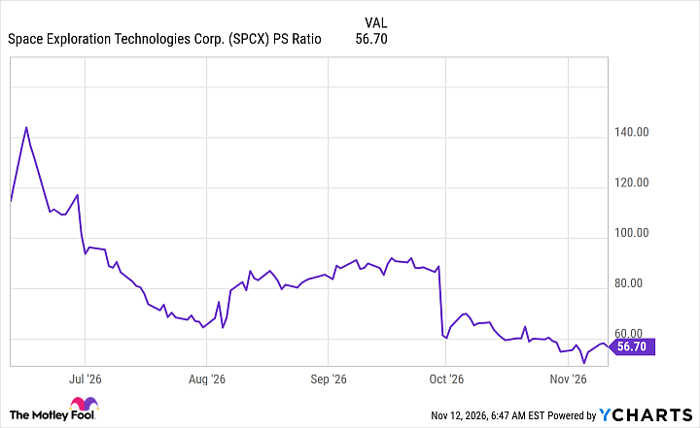
SPCX PS Ratio data by YCharts
Most big tech stocks trade for about 10 times sales, or 20 times sales if they are highly valued. So, at Anthropic’s projected $1.4 trillion valuation, that would price it about right. With how fast it’s growing overall, this price tag may start to look pretty cheap too. At its current growth rate, I think the $70- to $78-per-share price tag on Anthropic’s stock at IPO
Missed Nvidia in 2009? This Rare Signal Is Flashing Again
In 2009, a “Double Down” signal flashed for a little-known chipmaker called Nvidia. If you’d invested $5,000 then, you’d be sitting on $2,029,659 today.*
Now, for the first time in years, that same “Total Conviction” signal is flashing for a company 1/100th the size of Nvidia. It’s a key player in the $1.8 trillion space race, and with the stock recently sitting 20% off its highs, the window to get in early is closing fast.
Continue »
*Stock Advisor returns as of November 18, 2026.
Keithen Drury has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Space Exploration Technologies. The Motley Fool has a disclosure policy.