Key Points
-
AI infrastructure players are benefiting from the AI boom, but they’ve spent heavily to reap rewards.
-
This particular company could continue to win big down the road.
-
Artificial intelligence (AI) hyperscalers are spending hundreds of billions of dollars on building out the data centers needed to meet demand — and this has weighed on their share price performance at times this year. Investors have worried that these market giants may be overspending and that the revenue opportunity could fall short.
Of course, there’s always a certain amount of risk when looking into the future and considering demand down the road. This is the case for many areas — not just AI. But investors may feel a bit more worried about AI since it’s so new.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a “Double Down” signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same “Total Conviction” signal is flashing for a company 1/100th the size of Nvidia. Continue »
Still, some of the biggest hyperscalers have well-established businesses that generate significant revenue, and this allows them to comfortably invest in the build-out. Meanwhile, they also have their finger on the pulse of the market, so they have a sense of the capacity that should be needed, and are taking steps to manage the build-out wisely.
With this in mind, if I could buy and hold only one AI hyperscaler through 2030, it would be this one.
Two main businesses to power earnings
This particular company has two significant businesses that power its earnings: e-commerce and cloud computing. I’m talking about Amazon (NASDAQ: AMZN). You probably know this company best for its e-commerce business, one that operates around the world and sells everything from essentials to mass merchandise. This brings in enormous revenue, but the true profit driver at Amazon is its cloud computing business, Amazon Web Services (AWS). In the recent quarter, AWS accounted for 60% of the company’s total operating income.
Through AWS, Amazon sells general cloud services as well as a vast portfolio of AI products and services — including Amazon’s in-house-developed chips. This custom chip business is seeing tremendous growth, reaching a $25 billion annual revenue run rate in the second quarter. It also climbed in the triple digits from the year-earlier period.
Amazon aims to make a big move late next year by offering its Trainium AI chips externally for the first time; prior to this, they were used internally and as part of AWS services. This is one reason I would buy Amazon stock right now and keep adding to the position. Sales of these chips could create an interesting new revenue growth opportunity, and revenue is realized as soon as Amazon provides the chips to the customer.
Demand for core services
I also like Amazon for its well-established leadership in e-commerce and cloud, which supports earnings growth even as the company invests in the newish growth area of AI. It’s also important to keep in mind that AWS is seeing tremendous demand for core AWS services — ones that aren’t related to AI — so the business doesn’t depend on AI alone.
Amazon has a solid track record in investing and generating returns, as it’s done this with the core AWS business, and we can see this reflected in the chart below.
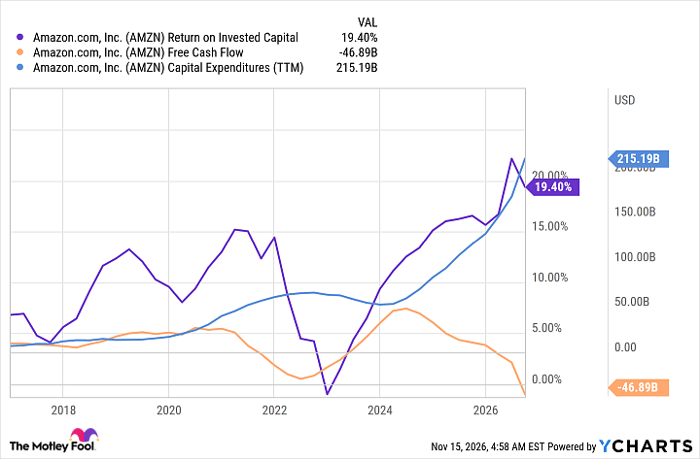
AMZN Return on Invested Capital data by YCharts
It’s normal that free cash flow dips as Amazon invests heavily in a particular area, but the company has demonstrated its ability to spend wisely — and grow thanks to that spending.
Finally, to operate, AI requires the chips and general capacity that Amazon offers. This means that as AI is used to address real problems and is applied to various tasks at companies and in our daily lives, this compute is needed. All of this supports the idea that the AI market will continue to expand, reaching into the trillions of dollars in the years to come.
Amazon recently said it expects to have two trillion-dollar businesses within the coming five to 10 years: its stores business and AWS should both reach $1 trillion in annual revenue.
Today, Amazon trades at 27x forward earnings estimates, which isn’t its cheapest this year but is still very reasonable. So, around these levels, if I could only buy and hold one AI hyperscaler through 2030, it would be Amazon.
Should you buy stock in Amazon right now?
Before you buy stock in Amazon, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Amazon wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004… if you invested $1,000 at the time of our recommendation, you’d have $335,171!* Or when Nvidia made this list on April 15, 2005… if you invested $1,000 at the time of our recommendation, you’d have $1,000,640!*
Now, it’s worth noting Stock Advisor’s total average return is 823% — a market-crushing outperformance compared to 208% for the S&P 500. Don’t miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of November 16, 2026.
Adria Cimino has positions in Amazon. The Motley Fool has positions in and recommends Amazon. The Motley Fool has a disclosure policy.