Key Points
-
Lucid has previously identified $1.4 billion in cash-flow improvement opportunities, but how fast can it turn this into tangible results?
-
Delaying Cosmos was likely the right business decision in the near term, but it can’t be sidelined indefinitely.
-
Investors will want to see progress when Lucid releases its third-quarter financials after market close today.
-
Lucid (NASDAQ: LCID) investors already know how many vehicles the company delivered during the third quarter. When financial results arrive later today, the more important question will be what management has accomplished beyond moving vehicles out the door. The company has impressive technology and ambitious plans. Shareholders could use a little less promise and a little more progress.
Two updates deserve investor attention: Whether its operating reset is delivering results, and whether its next major vehicle program is moving forward.
Missed AI’s “Act 1”? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn’t buy Nvidia in 2005. But according to our analysts, we’re only at the end of “Act 1″—the R&D phase. “Act 2” is the global rollout. Continue »
1. Is the reset producing results?
Lucid identified $1.4 billion in cash-flow improvement opportunities for 2026 across inventory, capital expenditures, and operating expenses. That’s a meaningful target considering the company desperately needs to curb cash burn. But identifying savings and delivering them are two different things. The good news is we already have a hint at the company reducing vehicle inventory from its recent third-quarter production and deliveries release. Lucid delivered 3,806 vehicles while producing 2,954, saying it was converting existing inventory into customer deliveries and freeing capital tied up in sitting inventory as part of the reset.
Now, investors need the financial follow-through. How much cash improvement has actually been achieved? Maybe more importantly, how much came from selling inventory, reducing ongoing expenses, or pushing investment spending into another period?
It’s one thing to make a quarterly earnings release look good, and it’s another to generate meaningful cash-flow improvements to extend runway of operations and potential turnaround. Selling excess inventory can release cash, but the same vehicle can’t be sold twice. Cutting recurring expenses can help beyond the current quarter. Delaying capital expenditures may preserve cash today while leaving a bill for later — not that helpful for long-term investors.
Management doesn’t need to make the turnaround look effortless. It needs to show that the plan is becoming more than a presentation slide.
2. Is Cosmos moving closer?
Lucid’s delayed Cosmos vehicle and midsize platform remain central to its effort to reach a broader customer base. On the second-quarter call, management pushed back its launch in 2027 without committing to an exact date, while describing a second-half production ramp-up at its Saudi Arabian AMP-2 factory.
Those are different milestones. A launch announcement isn’t the same as a factory producing meaningful volumes. To be fair, the delay isn’t so much a red flag as it is practical, because Lucid still has plenty of kinks to work out in the production of its electric Gravity SUV. In a perfect world, sure, rushing its more affordable Cosmos and accompanying platform would be great. But in the real world, bringing the Cosmos to production too soon, with so much on the line for the EV maker, wouldn’t be cost-effective or ideal.
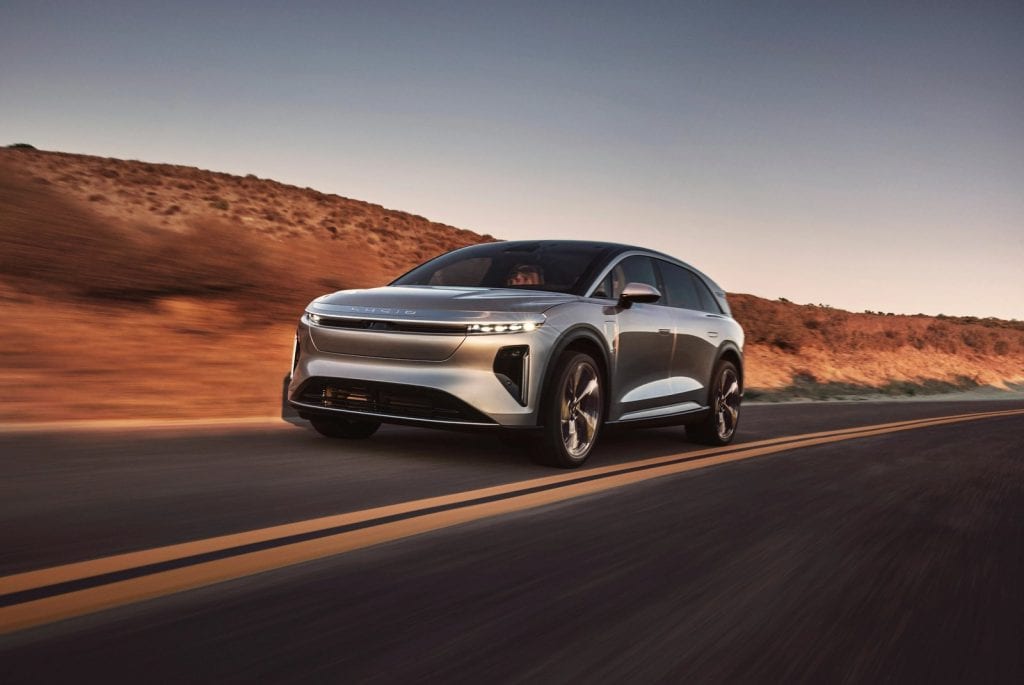
Investors should listen for progress on factory commissioning, supplier readiness, and vehicle validation. Supplier readiness is a question Wall Street analysts should be ready to ask about during the Q&A, as Lucid has hit multiple production speed bumps due to supplier bottlenecks and other related issues. Management has identified those areas as important to the program, making them more useful checkpoints for investors to remember, rather than another attractive prototype photograph — we already know Lucid makes fantastic-looking EVs.
Rivian (NASDAQ: RIVN) offers a timely comparison: Its R2 became its best-selling vehicle in the third quarter. A broader-market model can quickly change the sales mix once it reaches customers. Lucid still needs to execute that transition and prove it can keep up with Rivian, which it has failed to do with gross profit progress and shareholder dilution.
What it all means
Lucid needs to preserve cash while preparing products that can grow the business. Improving one side while neglecting the other won’t finish the job. The coming third-quarter report doesn’t need to deliver a miracle, and that’s good because it’s unlikely. However, measurable reset progress with cash flow and credible product milestones would give investors something more useful: evidence that Lucid is making some progress.
Should you buy stock in Lucid Group right now?
Before you buy stock in Lucid Group, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Lucid Group wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004… if you invested $1,000 at the time of our recommendation, you’d have $341,966!* Or when Nvidia made this list on April 15, 2005… if you invested $1,000 at the time of our recommendation, you’d have $1,146,819!*
Now, it’s worth noting Stock Advisor’s total average return is 852% — a market-crushing outperformance compared to 203% for the S&P 500. Don’t miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of November 9, 2026.
Daniel Miller has no position in any of the stocks mentioned. The Motley Fool has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy.