Key Points
-
Palantir’s revenue is soaring, and the company lifted several full-year forecasts.
-
The software company has seen business and its stock price take off amid the AI boom.
-
Palantir Technologies (NASDAQ:PLTR) has been one of the early winners of the artificial intelligence (AI) boom. The company sells AI-driven software that helps customers aggregate and make better use of their data. Customers have flocked to Palantir’s software as it offers them an opportunity to easily apply AI to their needs — without having to develop a platform on their own.
This has translated into tremendous growth for Palantir over the past couple of years, and this continued in the company’s latest blowout earnings report. Third-quarter revenue soared in the double digits, and Palantir lifted several full-year forecasts.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a “Double Down” signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same “Total Conviction” signal is flashing for a company 1/100th the size of Nvidia. Continue »
On top of this, Palantir did one thing in particular for the first time ever — and this is something that could determine what comes next. Is the stock a buy?
Image source: Getty Images.
Introducing customers to AIP
So, first, let’s talk a bit about Palantir’s business. The company has been around for more than 20 years, offering platforms that help customers leverage the power of their data. A few years ago, Palantir launched its Artificial Intelligence Platform (AIP), integrating large language models into its system. The company holds bootcamps to introduce customers to AIP, and through these sessions, they can go from zero to a use case in a matter of hours.
This has proven to be successful, as earnings have taken off at Palantir, and investors have piled into the stock to benefit.
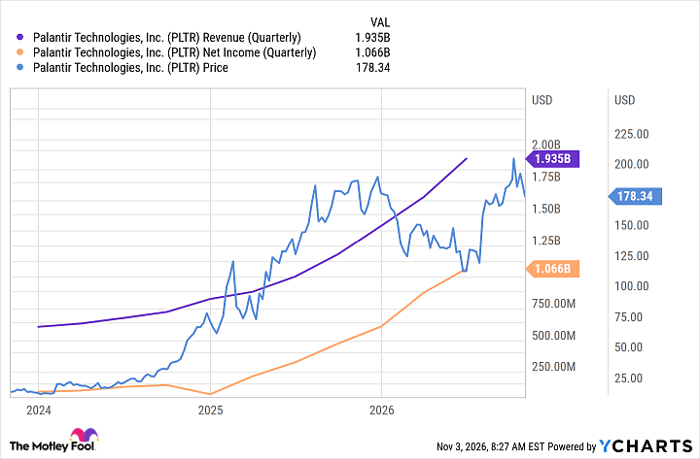
PLTR Revenue (Quarterly) data by YCharts
The recent quarter represented another wave of growth for Palantir, with the company delivering a 96% increase in revenue to $2.3 billion and a Rule of 40 score of 158%. This metric measures a software company’s ability to balance growth with profitability, and a level of 40% is seen as good. So, at 158%, which represents the 13th straight quarterly gain, Palantir truly is winning.
The company, confident about the full year, raised its revenue forecast as well as forecasts for U.S. commercial revenue, adjusted income from operations, and adjusted free cash flow.
Now, let’s consider the one thing in particular that Palantir did for the first time ever: Palantir’s U.S. commercial revenue surpassed its U.S. government revenue. They came in at $984 million and $953 million, respectively. And while the former advanced in the triple digits, the latter rose in the double digits.
Broadening the revenue stream
Though government revenue remains a core part of the Palantir story, this shows a clear shift into the commercial market. It’s significant because for most of the company’s history, it’s relied on government contracts for growth. Today, it has greatly broadened its revenue stream, and this increasing number of clients means less risk. Palantir had fewer than 20 U.S. commercial customers a few years ago, and now, that number has grown to more than 600.
I see this as a significant driver of growth moving forward as companies look for ways to apply AI quickly and easily — without having to start from scratch on their own.
Considering all of this, is Palantir a buy right now? It’s important to consider your investing strategy and comfort with risk before deciding. Cautious investors may not like certain elements, such as Palantir’s valuation. Though it’s come down considerably from earlier levels, the stock is still expensive at more than 100x forward earnings estimates.
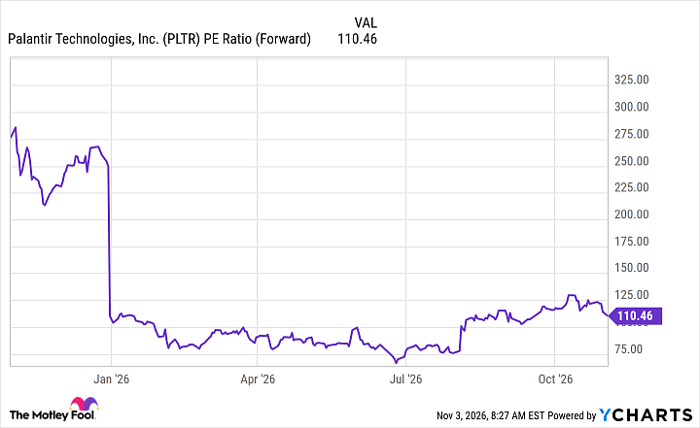
PLTR PE Ratio (Forward) data by YCharts
Some investors might also worry about slowing growth in new U.S. commercial contract value; the company closed $1.4 billion in the third quarter, representing 11% growth, while in the second quarter, this metric advanced 153% to $2.1 billion. That said, contract signings may not always translate into linear growth; growth could ebb and flow while still supporting solid earnings gains over time.
Palantir may not be the best investment for cautious investors. But considering the company’s track record of growth in recent years and the emergence of the commercial customer as a major growth driver, the stock makes a great buy for more aggressive investors who aim to hold on for the long run.
Should you buy stock in Palantir Technologies right now?
Before you buy stock in Palantir Technologies, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Palantir Technologies wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004… if you invested $1,000 at the time of our recommendation, you’d have $336,195!* Or when Nvidia made this list on April 15, 2005… if you invested $1,000 at the time of our recommendation, you’d have $1,241,567!*
Now, it’s worth noting Stock Advisor’s total average return is 875% — a market-crushing outperformance compared to 208% for the S&P 500. Don’t miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of November 4, 2026.
Adria Cimino has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Palantir Technologies. The Motley Fool has a disclosure policy.