Key Points
-
Home Depot’s growth has been since the pandemic ended.
-
It dominates home improvement retail in a duopoly with Lowe’s.
-
The company has a long track record of delivering strong operating margins and ROIC.
-
Home Depot (NYSE: HD) is a classic blue chip stock.
The company pioneered the big-box home improvement retail category, opening its first store in the late 1970s at a time when smaller hardware stores dominated the landscape.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a “Double Down” signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same “Total Conviction” signal is flashing for a company 1/100th the size of Nvidia. Continue »
These days, Home Depot has more than 2,000 stores worldwide and earns wide profit margins and a high return on capital, a sign of its competitive advantage.
However, the stock has not been a winner in recent years. Like other stocks with exposure to the housing market, Home Depot has disappointed, as shares are actually down 11% over the last five years, badly underperforming the S&P 500 during that time, as you can see from the chart below. 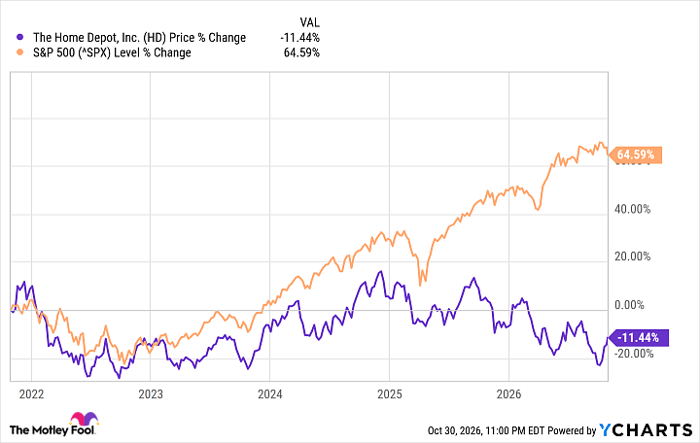
HD data by YCharts
Despite the results, I still think Home Depot is worth holding for the next decade. Here are four reasons why.
1. A strong set of competitive advantages
Along with rival Lowe’s, Home Depot is part of a duopoly in the home improvement retail segment.
The two companies have unmatched scale, reach, technology, and product range, which gives them significant market share in a fragmented industry.
Home Depot has differentiated itself from Lowe’s in some important ways as well. Compared to Lowe’s, the company is known for its focus on the professional contractor segment, and it now sees that as its primary growth opportunity. It acquired SRS Distribution, a building materials distribution company, to lean into the pro segment and grow that business.
The company has also invested heavily in omnichannel capabilities, making it easy for customers to order through its app for delivery or in-store pickup. It even offers digital project-planning apps to help consumers figure out what they need and get their projects done.
2. Its industry leadership position is solid
Unlike some other retail categories, Home Depot faces little risk from disruption. It’s not an easy category for a company like Amazon to gain market share in, as many of its SKUs are heavy and bulky, like lumber. Its stores also serve as distribution hubs, enabling easy pickup of e-commerce orders.
A pure-play e-commerce company wouldn’t be able to compete with it, and it’s hard to see another brick-and-mortar retailer expanding to match Home Depot and Lowe’s.
3. The housing market will eventually bounce back
The housing market has been virtually frozen since the pandemic ended, which is the main reason why Home Depot has struggled to grow.
The combination of the lock-in effect from low mortgage rates during the pandemic, high housing prices, and now high mortgage rates has kept out potential buyers. However, the housing crisis is a well-known problem in the country, and there’s an estimated shortage of around 4 million homes. It may take lower interest rates or a political push, but eventually there will be a rebound in the housing market, and Home Depot will be well-positioned to take advantage.
4. It’s a profit machine
A lot of brick-and-mortar retailers rely on high volumes and low margins, but Home Depot does high volume at high margins.
In its most recent earnings report, the company forecast an operating margin of 12.5%, though historically that number has been closer to 15%, and Home Depot could likely get back there in a healthier housing market. In 2025, the company had a return on invested capital of 25.7%.
Overall, Home Depot has the combination of share buybacks, dividends, and growth potential to deliver results for investors. It has historically been a big winner on the stock market, and with a little help from the housing market, it should get back to outperforming over the next decade.
Should you buy stock in Home Depot right now?
Before you buy stock in Home Depot, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Home Depot wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004… if you invested $1,000 at the time of our recommendation, you’d have $334,793!* Or when Nvidia made this list on April 15, 2005… if you invested $1,000 at the time of our recommendation, you’d have $1,257,420!*
Now, it’s worth noting Stock Advisor’s total average return is 874% — a market-crushing outperformance compared to 209% for the S&P 500. Don’t miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of October 31, 2026.
Jeremy Bowman has positions in Amazon and Home Depot. The Motley Fool has positions in and recommends Amazon and Home Depot. The Motley Fool recommends Lowe’s Companies. The Motley Fool has a disclosure policy.