Key Points
-
Tesla’s automotive gross margins improved, signaling strong demand.
-
Concerns about capital spending have eased with revised forecasts.
-
Robotaxi rollout is progressing, with FSD v15 a key milestone.
-
Although Tesla’s (NASDAQ: TSLA) earnings call certainly wasn’t as polished as the Space Exploration Technologies one the previous day, it was no less compelling. The company met three key benchmarks many investors were looking for in Tesla, and investors have reason to feel more positive about the stock as a result. Here’s why.
Tesla’s earnings: Substance over presentation
The key to the medium-term investment case for Tesla is its Robotaxi rollout, how it can finance it (and its other investments, such as Optimus), and whether it retains its leadership position in electric vehicles (EVs) to continue self-funding its development. All three issues were addressed, directly or indirectly, in the benchmarks and numbers from the company’s third-quarter earnings report and presentation.
Missed AI’s “Act 1”? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn’t buy Nvidia in 2005. But according to our analysts, we’re only at the end of “Act 1″—the R&D phase. “Act 2” is the global rollout. Continue »
Automotive gross margin recovery
Gross margins matter because they are key indicators of a company’s pricing power, competitiveness, and ability to generate future earnings growth and cash flow. Going back to the second quarter, Tesla reported a big increase in sequential automotive sales (from $15.5 billion in the first quarter to $20 billion in the second quarter). Still, the market was concerned by the drop in sequential gross profit margin (excluding regulatory credit sales) from 19.2% to 16.3%.
The key question going into the third quarter was whether the number would recover or a further decline would signal a loss of Tesla’s competitiveness as it was forced to offer financial incentives to boost sales. The answer is in the chart, with a sequential improvement to 18.3% signaling strong demand. This was confirmed on the earnings call, with Chief Executive Officer Elon Musk noting, “Demand is growing rapidly for our vehicles. It’s exceeding our production by a significant margin.”
With global vehicle inventories down to just 11 days from 27 days at the end of the first quarter, it’s unlikely Tesla needs to offer significant financial incentives now.
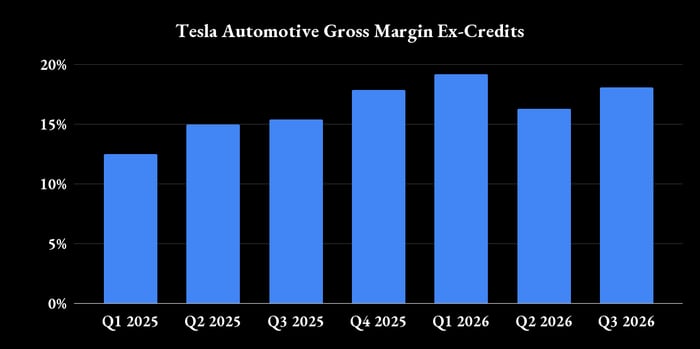
Data source: Tesla presentations. Chart by the author.
Tesla eases cash flow concerns
Let’s face facts: The Robotaxi rollout has been much slower than Musk estimated last year. As such, cash flow projections for Tesla from recurring robotaxi earnings have been pushed out.
At the same time, management has raised expectations for up-front capital expenditure (capex) this year, forecasting full-year capex of more than $20 billion in January, then more than $25 billion in April, and again in June. However, Chief Financial Officer Vaibhav Taneja dialed back expectations to “approximately $20 billion for the current year as a result of managing our capital deployment efficiently.”
This may sound esoteric, but it’s actually highly significant, given that Tesla lined up $30 billion in credit, raising concerns that it might not be able to self-fund its investment plans amid robotaxi rollout delays and capex requirements. The update soothed those concerns.
Image source: The Motley Fool.
The Robotaxi rollout is on track
Finally, it’s a real positive that expectations for the Robotaxi rollout, and for its two-seat Cybercab, now appear to be consistently maintained. Although social media is fixated on how many Robotaxis and Cybercabs are joining the fleet and how many cities are covered, the reality is that Tesla needs to get Robotaxi/Cybercab operational in a model that can then be rapidly scaled.
The key to scaling comes from ironing out operational issues (running a robotaxi network, etc.) and, as management has repeatedly outlined this year, the validation and release of its next major upgrade to its full self-driving (FSD) software, namely v15. On the earnings call in April, Musk said v15 would be out “hopefully by the end of this year, but certainly by early next year.” Fast forward to the July call, and Tesla’s AI head, Ashok Elluswamy, said that robotaxis were using early versions of v15.
The subject matter came up again on the recent earnings call, with a question from Morgan Stanley analyst Andrew Percoco asking whether the bottlenecks on Robotaxi/Cybercab were regulatory-driven. Elluswamy responded by outlining some software and operational factors that Tesla is still working on, and concluded, “So it’s not purely regulatory or something like that. It is technology-driven, but we do see that pretty quickly becoming regulatory, perhaps in Q1 or Q2 time frames.”
In other words, that’s the time frame for when v15 FSD should be released, enabling a ramp-up in Robotaxi/Cybercab deployment. This is consistent with what management said earlier.
What it means to investors
The slow rollout of Robotaxi/Cybercabs has no doubt frustrated investors, but it looks like it’s on track now and in line with the outlook management provided. Automotive gross margins are a sign of Tesla’s competitiveness, and concerns about its capital spending plans should ease after this earnings report.
All told, investors should feel better about their Tesla stock after the report.
Missed AI’s “Act 1”? Act 2 Could Be 14x Bigger
Most investors think they missed the AI boat because they didn’t buy Nvidia in 2005.
But according to our analysts, we’re only at the end of “Act 1″—the R&D phase. “Act 2” is the global rollout, a massive technology build-out that Google’s CEO says could be more profound than fire or electricity.
While everyone watches the chip designers, one “backbone” company provides the critical technology that Nvidia and AMD literally cannot function without. We’ve detailed this under-the-radar player in our new AI Playbook.
Continue »
Lee Samaha has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Tesla. The Motley Fool has a disclosure policy.