Key Points
-
One of the most-held stocks by hedge fund managers in September was Broadcom.
-
The month prior, they were mostly shorting it.
-
Here’s why Broadcom is a buy.
-
We spend a fair bit of time covering and commenting on the investment moves made by leading hedge fund managers, such as Ken Griffin at Citadel, to inform investors about what some of the experts in the field are seeing.
Market intelligence firm Data Insights tracks the stocks that hedge funds buy and sell. Specifically, it produces a monthly crowding report that examines the most popular long and short positions held by hedge funds and institutional investors.
Missed AI’s “Act 1”? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn’t buy Nvidia in 2005. But according to our analysts, we’re only at the end of “Act 1″—the R&D phase. “Act 2” is the global rollout. Continue »
September was a rocky month for large caps, as the S&P 500 (SNPINDEX: ^GSPC) fell, partly due to the Federal Reserve’s decision to raise interest rates. But hedge fund managers saw this as a buying opportunity, particularly for large tech stocks.
Of the 10 stocks that hedge funds held the most in September, Amazon (NASDAQ: AMZN) was the most popular, followed by Microsoft (NASDAQ: MSFT) and Applied Materials (NASDAQ: AMAT). Nvidia (NASDAQ: NVDA), Meta Platforms (NASDAQ: META), and Broadcom (NASDAQ: AVGO) were also in the top 10.
One of the biggest movers in the group was AI chipmaker Broadcom, which flipped from bearish in August, when it was mostly shorted, to bullish in September, when it was among the most-held long stocks.
Why are hedge funds back on board with Broadcom? Should you be, too?
Long on Broadcom
Broadcom reported third-quarter earnings on Sept. 2 and posted impressive gains. Revenue jumped 86% year over year to $29.6 billion, beating estimates, while net income rose 216% to $13.1 billion or $2.68 per share. Its AI semiconductor revenue surged 221% year over year and 54% from the previous quarter to $16.7 billion. This also blew away estimates.
So what’s the problem?
Some analysts didn’t think the firm’s forward guidance was good enough. But let’s put this into perspective: Broadcom’s revenue growth is expected to increase 93% year over year to $34.8 billion in Q4. Those gaudy projections were just short of analysts’ estimates of $35.03 billion.
Further, the AI semiconductor revenue is expected to accelerate to $21.7 billion in Q4, up 236% year over year. Broadcom raised its AI semiconductor revenue guidance to $58 billion for fiscal 2026, up from $56 billion. That’s up from $20 billion the previous year.
In 2027, the firm is targeting $115 billion in AI semiconductor revenue, up 98% from this year. And it expects to double that to $230 billion in 2028.
Why Broadcom is a buy
There have been other concerns about Broadcom, such as its declining gross margin, which is still attractive at 73%. But the decline stems from a rapidly growing mix of its lower-margin AI semiconductor business. However, that will eventually settle.
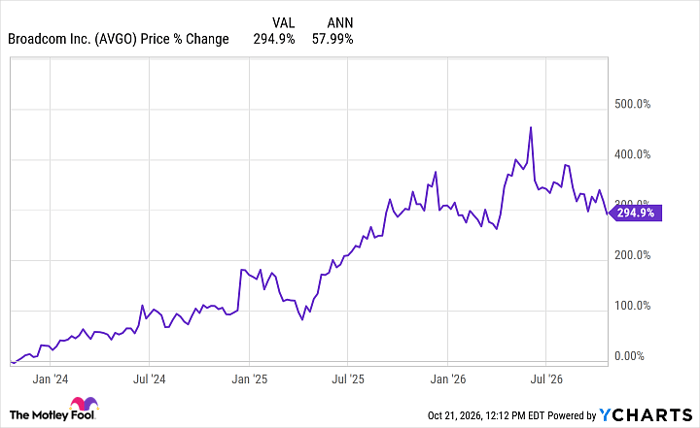
I think the major concern was its valuation, given its pretty incredible run over the past three years. Broadcom stock has averaged an annualized return of 59% over the past three years, with two years of triple-digit returns in 2023 and 2024.
AVGO data by YCharts
It was bound to come back to earth a bit after its price-to-earnings ratio soared to over 100 a little over a year ago.
I think hedge funds saw the post-earnings dip and decided to pile back into Broadcom, given the company’s strong growth and outlook for the next two years. Also, they likely saw the valuation as enticing, as Broadcom’s P/E ratio is down to 46, but its forward P/E is just 19 and its five-year P/E-to-growth (PEG) ratio is just 0.36.
Broadcom stock looks really attractive at these forward valuations, suggesting it may be undervalued relative to its long-term growth expectations. This should be a stock to put back on your radar.
Should you buy stock in Broadcom right now?
Before you buy stock in Broadcom, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Broadcom wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004… if you invested $1,000 at the time of our recommendation, you’d have $361,596!* Or when Nvidia made this list on April 15, 2005… if you invested $1,000 at the time of our recommendation, you’d have $1,303,935!*
Now, it’s worth noting Stock Advisor’s total average return is 910% — a market-crushing outperformance compared to 211% for the S&P 500. Don’t miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of October 24, 2026.
Dave Kovaleski has positions in Amazon. The Motley Fool has positions in and recommends Amazon, Applied Materials, Broadcom, Meta Platforms, Microsoft, and Nvidia. The Motley Fool has a disclosure policy.