Key Points
-
Nike is still reporting sales declines, and it’s expecting that to continue for fiscal 2027.
-
It’s facing big challenges in China as competitors take market share.
-
Nike stock is cheap, and its dividend yields 4.3% at the current price.
-
Nike (NYSE: NKE) may be the biggest and most well-known athletic wear company in the world, but its stock has plummeted over the past few years. It made a series of missteps that led to declining sales and losing some of its cachet, and it’s still struggling to get back to dominance.
The stock is a crushing 79% off its all-time high, but it’s up 17% from its 52-week low. Is the turnaround finally gaining steam? And, more importantly for investors, is now the time to buy?
Missed AI’s “Act 1”? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn’t buy Nvidia in 2005. But according to our analysts, we’re only at the end of “Act 1″—the R&D phase. “Act 2” is the global rollout. Continue »
Can Nike just do it?
Nike has been dealing with declining revenue for more than two years now, with some bright pockets. That’s a long stretch for what’s supposed to be the industry leader.
In the most recent quarter, the fiscal 2027 first quarter (ended Aug. 31), sales were down 4% from last year, but that’s less than some of its earlier quarters. Gross margin, which had been narrowing, expanded 0.6 points to 42.8%. Earnings per share (EPS) were $0.48, down from $0.49 last year, but higher than the $0.44 expected by Wall Street. The market liked the report, and the stock has been climbing ever since.
There’s a long road ahead, but there have been many signs of progress. Running was up double digits in the first quarter, as was the U.S. basketball business, and global football ( soccer). Nike had fallen behind in its sport lines, and it’s making its way back.
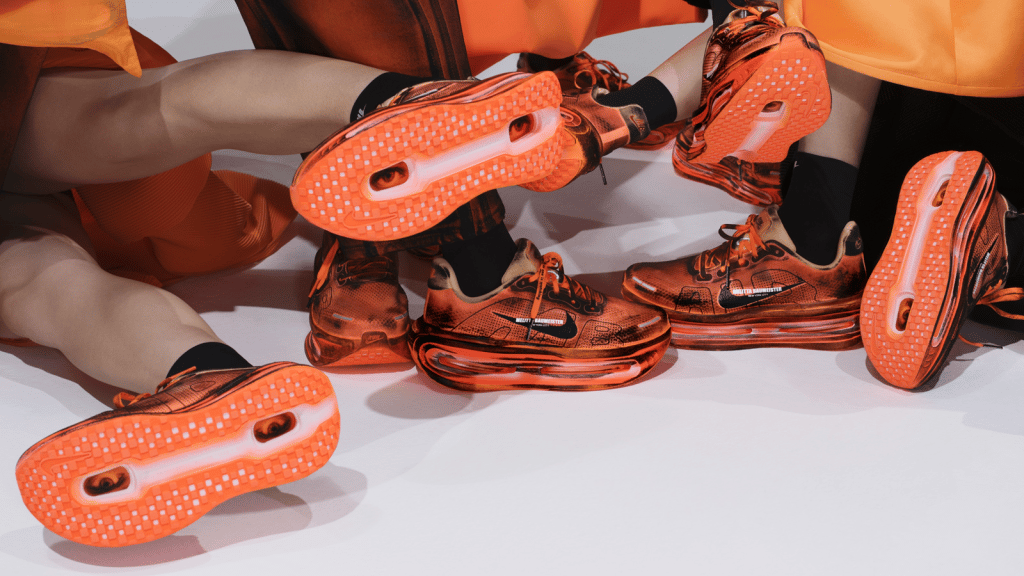
Some of Nike’s problems stemmed from a lack of innovation in sportswear, and it’s committed to restarting that engine, creating newness more frequently. Two of its running-inspired sportswear shoes, the P-6000 and the V5 Runner, grew by double digits in the quarter, and its newly launched Studio Fleece line was its best-performing apparel line. CEO Elliott Hill attributed the success to clarity, meaning determining each target clientele’s specific needs and serving them.
Big problems remain
Hill said that Nike is going to shrink some of its largest franchises, like the Jordan brand, which is oversupplied and doesn’t feel premium anymore. That is likely to lead to sales declines in these franchises in the beginning, before stabilizing, and that could be a drag on short-term growth.
But there are bigger problems that remain, notably China, which is one of its biggest and most important markets. Sales have been dropping precipitously in the region and fell 26% year over year in the first quarter. There is stiff competition from local brands, and Nike is aiming to clean up the business by tightening control over distribution to heighten the premium brand. It’s stopping distribution through third-party online sellers, and it’s developing lines to cater to the Chinese consumers.
However, that sounds strangely similar to some of the moves that brought it to this moment in the first place; under previous leadership, it curtailed relationships with wholesale partners and focused on its own direct-to-consumer channels, and customers found other brands, like On Holding and Berkshire Hathaway‘s Brooks at retailers instead. Will it have different results in China? Only time will tell.
Risks vs. reward
At the current price, Nike stock trades at a P/E ratio of 18, near its lowest level in 10 years. However, there’s good reason for that. At this price, though, its dividend yields 4.3%, which is excellent for passive income investors.
Management is still projecting a high single-digit decline in fiscal 2027, so there isn’t much to be hopeful about in the near future. Considering its array of challenges, investors may want to hold off on buying Nike stock, even at this cheap price. I’d wait for more progress, especially on the China business, before saying that this is a bargain.
Should you buy stock in Nike right now?
Before you buy stock in Nike, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Nike wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004… if you invested $1,000 at the time of our recommendation, you’d have $350,756!* Or when Nvidia made this list on April 15, 2005… if you invested $1,000 at the time of our recommendation, you’d have $1,363,905!*
Now, it’s worth noting Stock Advisor’s total average return is 922% — a market-crushing outperformance compared to 213% for the S&P 500. Don’t miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of October 22, 2026.
Jennifer Saibil has positions in On Holding. The Motley Fool has positions in and recommends Berkshire Hathaway, Nike, and On Holding. The Motley Fool has a disclosure policy.