Key Points
-
CoreWeave’s bonds have passed into “distressed” territory — a concerning milestone.
-
Nebius is in the same industry as CoreWeave and so it now has investors worried, too.
-
It has been a bad time to be a Nebius (NASDAQ: NBIS) or CoreWeave (NASDAQ: CRWV) shareholder. For the week of Oct. 12 to Oct. 16, each stock crashed 25%. That’s no small drop, and investors in these two are likely concerned.
But should they be? Or is it time to buy the dip? Let’s take a look.
Missed AI’s “Act 1”? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn’t buy Nvidia in 2005. But according to our analysts, we’re only at the end of “Act 1″—the R&D phase. “Act 2” is the global rollout. Continue »
CoreWeave caused the sell-off
The sell-off can be directly correlated to the yield on CoreWeave’s debt on the secondary market exploding to 15%. That’s a big deal, because the current risk-free yield on Treasuries hovers around 5%, so this debt is now classified as “distressed,” which is worse than “junk.”
This is basically the market telling investors that it does not believe that CoreWeave will be able to meet its debt obligations. As a result, its stock has sold off. Nebius is in the same industry, so its stock sold off in solidarity.
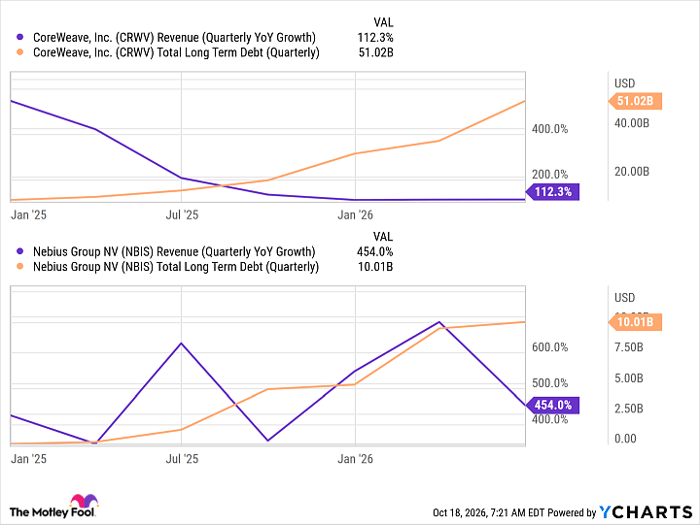
Both companies operate in the neocloud computing space, which deals in what is essentially cloud computing with a focus on artificial intelligence (AI). Neither CoreWeave nor Nebius has a core business to fund its massive data centers, so they must issue shares or take on debt to build out the data centers they need to compete with the AI hyperscalers. These two are growing incredibly fast, but they are using debt to do so.
CRWV Revenue (Quarterly YoY Growth) data by YCharts
The big concern here isn’t what happens to the debt now; it’s what will happen when debt needs to be issued later. Both companies will have to issue debt again to maintain their growth rates, and if the yields on the bonds are sky-high when they are issued, it may not be worth it. This could be a huge problem for these companies, and we’ll have to see if it persists.
So is it time to buy the dip on these two? I’m not sure. While I believe in the strength of the AI build-out and that CoreWeave and Nebius are two growing companies that could make a name for themselves, what’s going on now in the bond market could be a problem for future debt issuance. The core investment thesis is that they will have access to nearly unlimited cheap capital to build out cloud infrastructure. What happened in the past week has challenged this notion.
I currently own shares of Nebius, but not CoreWeave. I don’t plan on adding any more shares at the moment, but I’m also not selling. Sometimes best to let the dust settle before taking action.
Should you buy stock in CoreWeave right now?
Before you buy stock in CoreWeave, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and CoreWeave wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004… if you invested $1,000 at the time of our recommendation, you’d have $350,756!* Or when Nvidia made this list on April 15, 2005… if you invested $1,000 at the time of our recommendation, you’d have $1,363,905!*
Now, it’s worth noting Stock Advisor’s total average return is 922% — a market-crushing outperformance compared to 213% for the S&P 500. Don’t miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of October 22, 2026.
Keithen Drury has positions in Nebius Group. The Motley Fool has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy.