Key Points
-
October is when the Social Security Administration typically announces key changes to the program.
-
By mid-month, seniors should know what cost-of-living adjustment to expect.
-
There should also be news that impacts workers specifically.
-
For many people, October is a big month. It’s when the leaves start to change (which is a huge deal if you’re into that sort of thing), the weather gets cool and stays cool, and the pumpkin spice explosion really kicks into gear.
It’s also a big month for Social Security. And on Oct. 14, the Social Security Administration should be announcing three major updates to the program. Here’s what to look out for.
Missed AI’s “Act 1”? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn’t buy Nvidia in 2005. But according to our analysts, we’re only at the end of “Act 1″—the R&D phase. “Act 2” is the global rollout. Continue »
Image source: Getty Images.
1. The 2027 cost-of-living adjustment
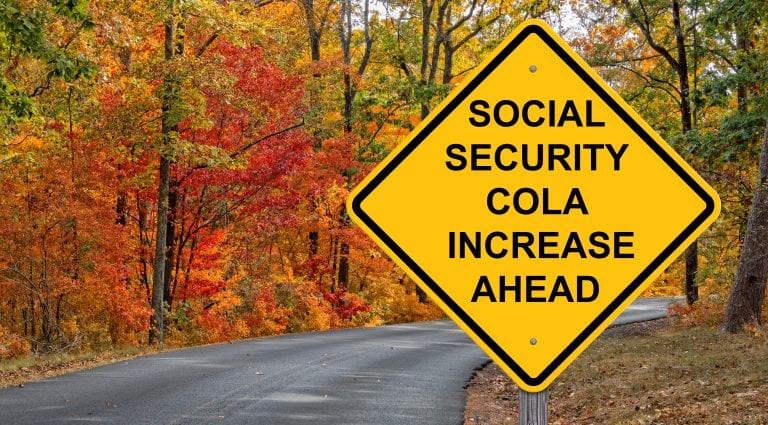
Each year, Social Security benefits are eligible for a cost-of-living adjustment, or COLA, that’s tied to inflation. Earlier this year, benefits rose 2.8%, but many seniors are hoping to see a larger boost in 2027.
Current estimates are calling for a 2027 COLA in the 3.5% to 3.6% range. But ultimately, September’s Consumer Price Index could push the COLA upward or downward.
An important thing to remember is that seniors enrolled in Medicare pay their Part B premiums out of their Social Security checks. If there’s a big increase in the cost of Part B next year, it could erode the upcoming COLA, even if it’s generous.
2. The new earnings-test limits
Social Security’s earnings test applies to people who work while receiving benefits prior to full retirement age. In that scenario, working is allowed. But once wages exceed a certain level, benefits can be withheld on a temporary basis.
In 2026, Social Security recipients have $1 in benefits withheld per $2 of earnings above $24,480, assuming full retirement age won’t be reached by the end of the year. If it will, that limit rises to $65,160, and from there, $1 in Social Security is withheld per $3 of earnings.
The earnings-test limits typically increase in line with wage growth. So if you work while collecting Social Security and are subject to the earnings test, there’s a good chance you’ll be able to earn more money in 2027 before it negatively impacts your benefits.
3. A new wage cap
Social Security gets most of its funding from payroll taxes. Workers pay into the program at a rate of 6.2% that’s matched by their employers.
Each year, there’s a limit set, known as the wage cap, that determines how much income can be taxed to fund Social Security. This year, the cap is $184,500. Next year’s cap is likely to be higher.
But whereas a higher earnings-test limit is good news for those affected, a higher wage cap is bad news for earners making over $184,500. It means people in that boat should expect to see their tax bills go up in 2027.
All told, there are a lot of big Social Security changes arriving later this month. Tune in on Oct. 14 for the big announcement so that you stay in the loop.
The $23,760 Social Security bonus most retirees completely overlook
If you’re like most Americans, you’re a few years (or more) behind on your retirement savings. But a handful of little-known “Social Security secrets” could help ensure a boost in your retirement income.
One easy trick could pay you as much as $23,760 more… each year! Once you learn how to maximize your Social Security benefits, we think you could retire confidently with the peace of mind we’re all after. Join Stock Advisor to learn more about these strategies.
View the “Social Security secrets” »
The Motley Fool has a disclosure policy.